

Businesses rely more on software every year, for their operations and for their decisions. As spending on software grows, one question keeps coming up: “Is it a fixed asset?” Deciding whether software can be treated as a fixed asset, and whether it belongs in the asset register, is essential for correct financial reporting and compliance.
The short answer: software you buy outright or build for your own long-term use is a capitalized, long-term asset, but strictly it is an intangible asset, amortized rather than depreciated. Software you rent as a subscription is usually an operating expense. Many US companies still present capitalized software within property and equipment and track it in the fixed asset register, which is why the question is so common.
This guide covers the definition of fixed assets, when software qualifies, how US GAAP treats each kind of software spending, a worked example, and how to keep software in your asset records.
Definition of Fixed Assets
Fixed assets are long-term resources a business uses to earn income, which it expects to use for more than one year and does not hold for sale. Buildings, equipment, machinery and vehicles are the classic examples. In accounting language they are property, plant and equipment: tangible assets that are depreciated over their useful lives.
Intangible assets are long-term resources with no physical form, such as patents, trademarks, customer lists and software. They are amortized over their useful lives instead of depreciated. Both are noncurrent assets, which is why software ends up in conversations about fixed assets.
Which Asset is Held as a Fixed Asset?
An asset is capitalized as a long-term asset when it meets all of these tests:
- Long-term use. It will be used for more than one accounting period, usually more than a year.
- Not for resale. It is used in operations, not held as inventory to sell.
- Depreciation or amortization. Its cost is spread over the years it is used.
- Above the capitalization threshold. It costs more than the minimum the company’s policy sets for capitalizing.
Tangible items that pass these tests are fixed assets. Intangible items such as software that pass them are capitalized as intangible assets. If you want a refresher on the line between short- and long-term assets, see current assets vs fixed assets.
Is Software a Fixed Asset?
Whether software is a fixed asset depends on how you get it, what it costs and how long you will use it:
| Type of software spending | US GAAP treatment | Asset or expense? |
|---|---|---|
| Perpetual license bought for internal use | Capitalized as internal-use software, amortized over its useful life | Asset |
| Software developed in-house for internal use | Costs in the development phase capitalized, others expensed | Asset, in part |
| Software embedded in equipment, such as a machine’s controller | Part of the equipment’s cost | Fixed asset, with the equipment |
| SaaS or cloud subscription | Expensed over the subscription term | Expense; a prepaid amount is a current asset |
| Implementation costs for a SaaS system | Capitalized if they qualify, amortized over the term of the arrangement | Asset, shown with prepaid costs |
| Maintenance and support fees | Expensed over the period covered | Expense |
| Training staff to use software | Expensed as incurred | Expense |
| Software developed to sell to customers | Separate rules for software to be sold | Asset, in part |
Purchased Software
A perpetual license for software such as an ERP system, design software or an accounting package is capitalized when its cost is above your threshold and you will use it for more than a year. Under US GAAP it falls under the internal-use software guidance in ASC 350-40, and it is amortized, usually straight-line, over its expected useful life.
Internally Developed Software
Software you build for your own use is capitalized only for the costs of developing it. Under ASC 350-40, costs in the preliminary project stage (evaluating options, choosing a vendor) are expensed. Costs in the application development stage (design, coding, installation and testing, including the payroll of employees working directly on it) are capitalized once management has committed to the project and it is probable it will be completed. Costs after the software is ready, such as training and maintenance, are expensed. Upgrades that add new functionality are capitalized.
In 2025 FASB issued ASU 2025-06, which replaces the project stages with a test of when it is probable the project will be completed and the software used as intended. It takes effect for annual periods beginning after December 15, 2027, and companies may adopt it earlier.
Subscription-Based Software (SaaS)
A software subscription is a service contract, not an asset you own, so the fees are an operating expense recognized over the subscription term. If you pay a year in advance, the unused portion sits on the balance sheet as a prepaid expense, a current asset, and is expensed month by month.
Capitalization vs. Expense
Capitalize software that you own or license for more than a year, that costs more than your capitalization threshold, and that you will use in the business. Expense subscriptions, maintenance, training, data conversion and software below the threshold.
Useful Life
Software you will use for more than one year can be capitalized. Useful lives for capitalized software are usually short, commonly three to five years, because software is replaced or upgraded more often than equipment. Set the life in your accounting policy and apply it consistently.
Also Read: Fixed Asset Tracking & Asset Management: Are They Both Same?
Is Software a Fixed Asset or an Intangible Asset?
Software is an intangible asset. It has no physical substance, so under both US GAAP and IFRS it is classified as intangible, and its cost is amortized.
Two practical points blur the line:
- US presentation. US GAAP does not set one balance sheet line for capitalized internal-use software. Some companies show it with intangible assets, and many include it in property and equipment.
- Software integral to hardware. Under IFRS, software that a machine cannot run without, such as an operating system in a piece of equipment, is part of the equipment under property, plant and equipment. Software that is not integral is an intangible asset. US practice treats software bought with and inseparable from equipment the same way.
So “software fixed asset” in an asset register usually means capitalized software tracked alongside fixed assets, even though the balance sheet may call it intangible.
Is Software an Asset or an Expense?
Software is an asset when you control it for more than a year and its cost is above your threshold. It is an expense when it is a subscription, a service, or a cost that does not create future benefit, such as training. One purchase often produces both: the license and qualifying implementation work are capitalized, while training, data conversion and the first year of support are expensed.
Is a Software Subscription an Asset or an Expense?
A software subscription is an expense. Under US GAAP, a cloud or SaaS arrangement is a service contract unless you have the right to take the software and run it yourself, so the fees are expensed over the term.
The implementation costs are different. Costs to configure and set up a SaaS system that would be capitalized for internal-use software are capitalized and amortized over the term of the arrangement, including renewals you are reasonably certain to take. They are presented with prepaid costs, and the amortization is shown in the same line as the subscription fees.
IFRS differs here. Under IFRS, configuration and customization costs for a SaaS system are usually expensed, because the customer does not control the software. They are capitalized only if they create a separate intangible asset the customer controls.
Worked Example: Capitalizing an ERP License
A distributor buys a perpetual ERP license and implements it over four months. These are the costs:
| Cost | Amount | Treatment |
|---|---|---|
| Perpetual license | $60,000 | Capitalize |
| Consultants configuring and installing the software | $30,000 | Capitalize |
| Internal staff coding custom reports | $12,000 | Capitalize |
| Converting data from the old system | $5,000 | Expense |
| Training users | $8,000 | Expense |
| First-year maintenance and support | $12,000 | Expense over the year |
| Capitalized cost | $102,000 |
The company sets a five-year useful life and amortizes straight-line from the day the system goes live: $102,000 ÷ 5 = $20,400 a year, or $1,700 a month. The journal each month is a debit to amortization expense and a credit to accumulated amortization. After five years the software is fully amortized, even if it is still in use.
For tax, the rules differ from the books. Off-the-shelf software bought by a US business is generally depreciated straight-line over 36 months and may qualify for faster write-offs, while the rules for software development costs have changed several times in recent years. Confirm the current treatment with your tax adviser.
Criteria for Classifying Software as a Fixed Asset
Use these tests to decide whether a software purchase belongs on the balance sheet:
1. Cost of Acquisition
The cost must be above your capitalization threshold. Enterprise applications such as ERP, CRM and accounting systems usually are; a single desktop license usually is not.
2. Useful Life
The software must benefit the business for more than one year. A custom application a plant will use for years passes; a tool licensed for a three-month project does not.
3. Purpose
The software must be used in operations, such as inventory management or transaction processing, and not developed to sell. Software for sale follows separate rules.
4. Ownership
You must own the software or hold a license that lets you run it. Software bought outright or developed in-house qualifies; a subscription to software hosted by the vendor does not.
5. Depreciation or Amortization
Once capitalized, software is amortized over its useful life, usually straight-line. Software that is part of a piece of equipment is depreciated with that equipment.
Benefits of Treating Software as a Fixed Asset
1. Accurate Financial Reporting
Capitalizing software spreads its cost over the years it is used, so the income statement is not distorted by one large purchase. An ERP system capitalized at $102,000 costs $20,400 a year for five years instead of $102,000 in one.
2. Better Asset Management
Software in the register has an owner, a cost, a useful life and a renewal date, so it is reviewed like any other asset.
3. Tax Planning
Capitalized software is deducted over time for tax, and some purchases qualify for faster write-offs. Keeping software in the register makes those schedules easier to support.
4. Better Budget Planning
Knowing when software reaches the end of its useful life helps plan upgrades and replacements before they become urgent.
5. Improved Compliance
Auditors expect capitalized software to be supported by invoices, contracts and an amortization schedule that matches the general ledger.
Challenges in Treating Software as a Fixed Asset
1. Classification Complexity
Hybrid deals that combine a license, hosting, implementation and support need to be split into each part and treated separately. Read the contract before deciding.
2. Amortization Tracking
Each capitalized software asset needs its own start date, useful life and schedule. Spreadsheets break when lives change or upgrades are capitalized on top of the original cost.
3. Lifecycle Management
Software is retired more quietly than equipment. When a system is replaced, its remaining book value must be written off, which is easy to miss.
4. Compliance Requirements
Capitalization policies, development-stage evidence and impairment reviews all need documenting, so an auditor can follow each decision.
Keeping Software in Your Asset Records with Asset Infinity
Asset Infinity’s fixed asset management software keeps capitalized software in the same register as the rest of what you own:
- One record per asset. A software license can be its own asset with a category, cost, purchase date and expected life.
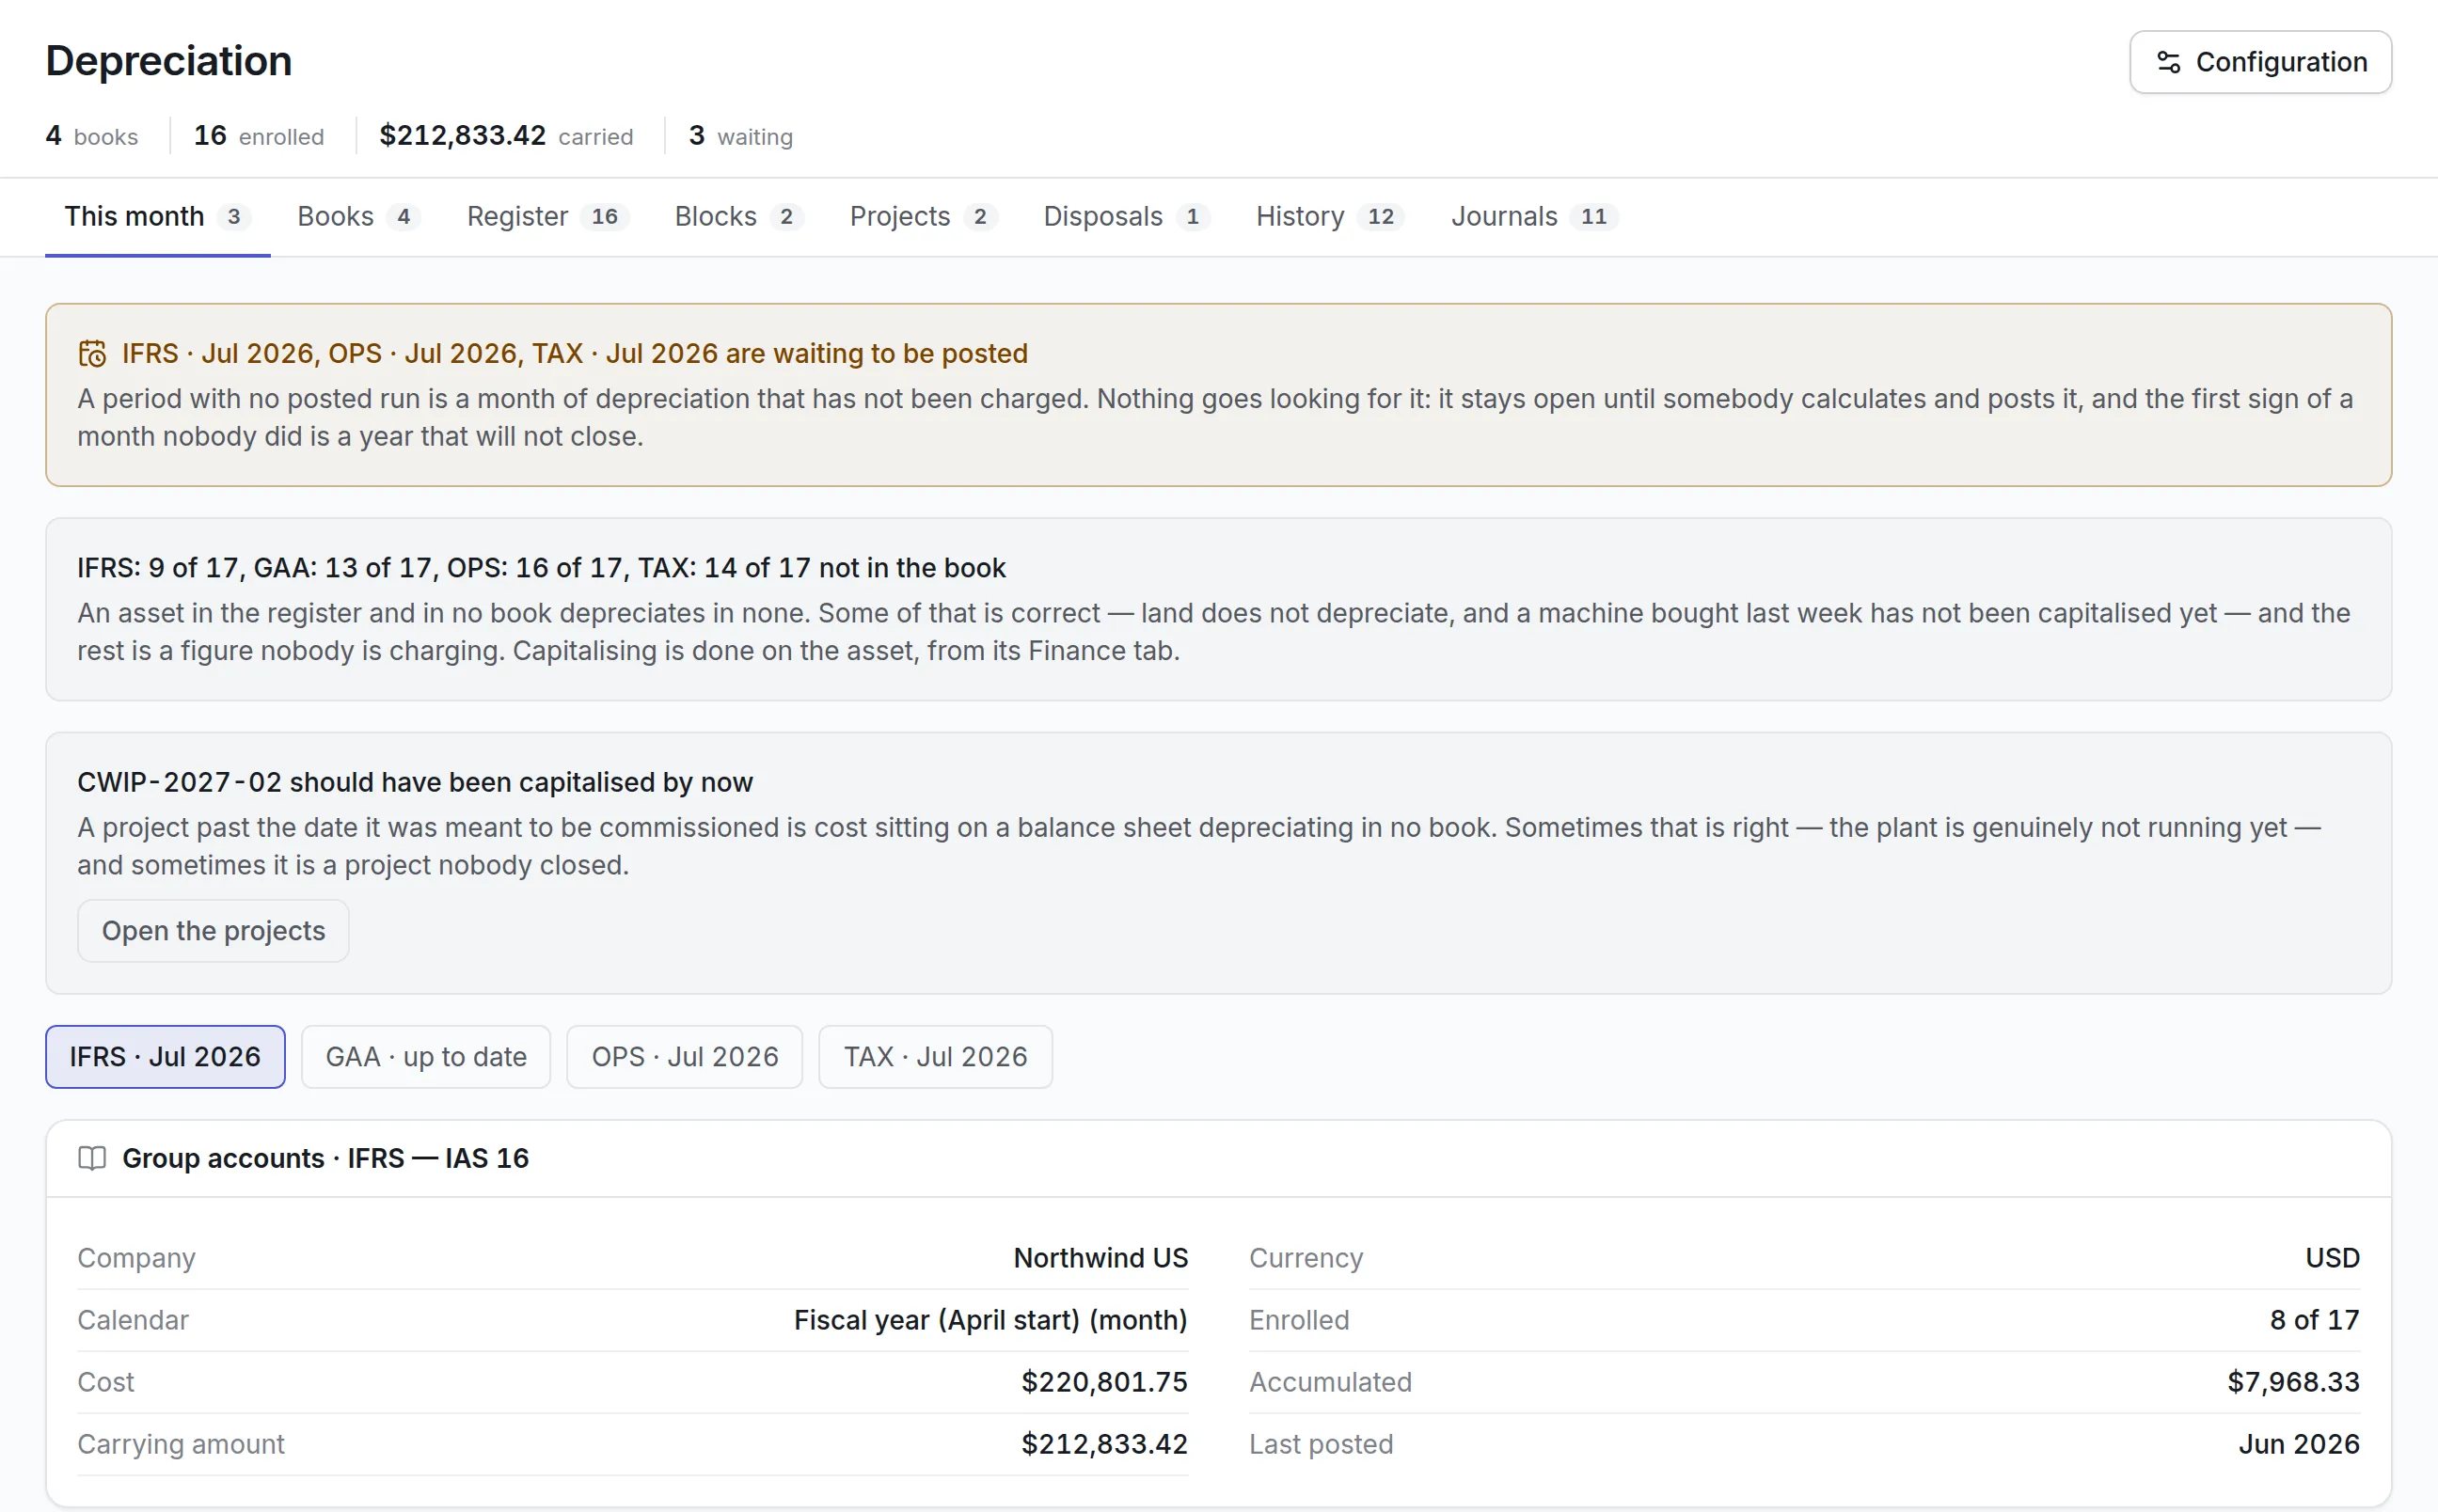
- Straight-line in every book. Straight-line, the method used to amortize most software, is one of the depreciation methods, and an asset can carry more than one book, such as one for the financial statements and one for tax.
- Periods posted to the ledger. Each period’s run is calculated, posted and can be reversed, with a journal export for the general ledger.
- Licenses counted against installs. Software license management counts installed software against the licenses you bought, per device, user, site or enterprise.
- Contracts and renewals. Support contracts can be recorded against assets, and a standard report lists warranty and contract expiry dates.
For the wider register, read how to prepare a fixed asset register.
FAQ on Software as a Fixed Asset
1. What is a fixed asset?
A fixed asset is a tangible, long-term resource used in the business, such as a building, machine or vehicle, that is expected to be used for more than a year and is depreciated.
2. Is software a fixed asset?
Software is an intangible asset, not strictly a fixed asset. Purchased or internally developed software used for more than a year and above your threshold is capitalized and amortized, and many companies track it with their fixed assets.
3. Is software an asset?
Yes, when you own or license it for more than a year and it is above your capitalization threshold. Subscriptions, training and maintenance are expenses.
4. Is a software subscription an asset or an expense?
A subscription is an expense recognized over its term. Any amount paid in advance is a prepaid expense, a current asset, until the period it covers.
5. Is software depreciated or amortized?
Capitalized software is amortized, usually straight-line over three to five years. Software that is part of a piece of equipment is depreciated with the equipment.