

Managing both assets and inventory matters for any business that wants to run efficiently and keep its financial records right. Both are valuable, but assets and inventory serve different purposes and need different ways of managing them. This guide explains the key differences between assets and inventory, how each one is reported and valued, and the practices that keep both under control.
The short answer first: inventory is an asset. It is a current asset on the balance sheet, because a business expects to sell it or use it up within a year or one operating cycle. When people compare “assets vs inventory”, they usually mean fixed assets vs inventory: fixed assets such as machinery, vehicles and buildings are noncurrent (long-term) assets that the business keeps and uses, while inventory is held to be sold or turned into products.
Is Inventory an Asset?
Yes. Inventory is an asset because the business owns it and expects it to bring in cash when it is sold. Under US GAAP it appears in the current assets section of the balance sheet, usually just below cash and accounts receivable.
Inventory covers three kinds of goods:
- Raw materials waiting to be used in production.
- Work in process, which is partly finished product.
- Finished goods (or merchandise, for a retailer) ready to sell.
What inventory is not is a fixed asset. It is not depreciated, and it does not sit in property, plant and equipment.
Is Inventory a Current Asset?
Inventory is a current asset. US GAAP defines current assets as cash and other assets a business reasonably expects to turn into cash, sell or consume within one year or within its normal operating cycle, whichever is longer. Inventory is the textbook example, because selling it is how most of that cash comes in.
| Question people ask | Plain answer under US GAAP |
|---|---|
| Is inventory an asset? | Yes. It is owned and expected to produce cash. |
| Is inventory a current asset? | Yes. It is listed with current assets on the balance sheet. |
| Is inventory a short-term asset? | Yes. “Short-term asset” and “current asset” mean the same thing. |
| Is inventory a long-term asset? | No, in almost every case. See the exception below. |
| Is inventory a fixed asset? | No. Fixed assets are kept for use, not for sale. |
| Is inventory depreciated? | No. Its cost becomes cost of goods sold when it is sold. |
Is inventory a long-term asset?
Normally no. Even inventory that takes more than a year to sell, such as aging whiskey or seasoned lumber, stays in current assets, because the operating cycle for those businesses is longer than a year. In rare cases a company holds more inventory than it expects to use in its operating cycle and classifies the excess as noncurrent, with a disclosure explaining why.
What Type of Asset Is Inventory?
Inventory is a current, tangible and operating asset:
- Current, because it is expected to be sold or used within the operating cycle.
- Tangible, because it is physical goods you can count.
- Operating, because it is part of the normal business of making and selling, not an investment.
It is also less liquid than cash or receivables, because it has to be sold first. That is why the quick ratio (acid-test ratio) leaves inventory out, while the current ratio includes it.
What Are Assets?
Assets are resources a business owns or controls that are expected to bring future economic benefit. They can be tangible, such as buildings and machinery, or intangible, such as patents, software and trademarks. On the balance sheet, assets are split into two groups by how long the business expects to hold them.
Types of Assets
- Current assets. Cash, accounts receivable, inventory, prepaid expenses and short-term investments. They are expected to turn into cash or be used up within a year or one operating cycle. They give the business the liquidity it needs to pay its bills.
- Noncurrent assets. Everything held longer than that. The largest group is usually fixed assets, reported as property, plant and equipment (PP&E): land, buildings, machinery, vehicles, furniture and computer equipment. Noncurrent assets also include intangible assets and long-term investments.
Fixed assets are bought to be used, not resold. Except for land, their cost is spread over their useful life through depreciation. Our guide to current assets vs fixed assets covers that split in more detail.
What Is Inventory?
Inventory is the raw materials, work-in-process items and finished goods that a business holds for sale or for use in production. Unlike fixed assets, inventory turns over quickly: it is bought, used or sold, and replaced. Good inventory management keeps enough stock to meet demand without tying up cash in goods that sit on the shelf.
Types of Inventory
- Finished goods. Products ready for sale. Retailers and manufacturers watch these closely to meet demand without overproducing.
- Raw materials. The components and materials used in production. Running short stops the line; holding too much ties up cash.
- Work in process (WIP). Partly completed products still in production, valued at the materials, labor and overhead put into them so far.
Many businesses also keep supplies, such as cleaning materials and maintenance spare parts. These are usually carried as a current asset or expensed when bought if the amounts are small.
How inventory is valued under US GAAP
Inventory is recorded at cost, using a cost flow method such as FIFO (first in, first out), LIFO (last in, first out) or weighted average cost. It is then tested for value:
- Inventory measured with FIFO or average cost is carried at the lower of cost and net realizable value.
- Inventory measured with LIFO or the retail method is carried at the lower of cost or market.
If goods are damaged, obsolete or worth less than they cost, the business writes them down and records a loss. Inventory is never depreciated.
Key Differences Between Assets and Inventory
The difference between assets and inventory comes down to purpose, time and accounting. In this comparison, “assets” means fixed assets, since inventory is itself a type of asset.
| Fixed assets | Inventory | |
|---|---|---|
| Purpose | Used to run the business | Held for sale or for use in production |
| Balance sheet section | Noncurrent assets (PP&E) | Current assets |
| Time held | More than one year | Within one year or one operating cycle |
| Examples | Machinery, vehicles, buildings, computers | Raw materials, work in process, finished goods |
| How cost is expensed | Depreciation over useful life (land is not depreciated) | Cost of goods sold when the item is sold |
| Measurement | Cost less accumulated depreciation and any impairment | Lower of cost and net realizable value (or cost or market for LIFO and retail) |
| Tracked by | Individual asset, with a unique asset number | Item or SKU, by quantity and location |
| Count | Periodic physical verification of each asset | Cycle counts and year-end stock counts |
| Leaves the books when | It is sold, scrapped or disposed of, with a gain or loss | It is sold, used or written off |
The same item can be either one
Whether something is inventory or a fixed asset depends on why the business holds it, not what it is. A forklift on a dealer’s lot is the dealer’s inventory. The same forklift working in a customer’s warehouse is the customer’s fixed asset. A computer at a retailer is inventory; on an accountant’s desk it is equipment.
Worked example: a bakery
A bakery buys a $30,000 oven and $4,000 of flour in the same month.
- The oven is a fixed asset. It goes into PP&E at $30,000. If it has a ten-year life and no salvage value, straight-line depreciation is $3,000 a year.
- The flour is inventory, a current asset. As bread is baked and sold, the flour’s cost moves into cost of goods sold. If $3,500 of it is used and sold in the month, $500 of flour inventory is left on the balance sheet.
Ten years later the oven still stands in the kitchen at a book value of zero. The flour was gone in weeks.
Common Challenges in Managing Assets and Inventory
- Mixing the two. Spare parts, tools and equipment bought for resale end up in the wrong records. Agree a capitalization policy and a clear rule for what counts as inventory, then apply it at purchase.
- Missing or idle fixed assets. Equipment moves between sites and people, and the register stops matching what is on the floor. A periodic count catches assets that were lost, moved or disposed of without being recorded.
- Stockouts and overstock. Too little stock stops work or loses sales; too much ties up cash and risks obsolescence. Reorder points and regular counts keep stock in range.
- Depreciation and valuation errors. Fixed assets in the wrong category are depreciated over the wrong life, and inventory that should have been written down overstates the balance sheet. Monthly reconciliation to the general ledger finds both early.
Best Practices for Managing Assets and Inventory
1. Keep a register for fixed assets
Give each fixed asset a unique number, a category, a location, a custodian and its cost, life and depreciation method. Our guide on how to prepare a fixed asset register walks through the fields.
2. Track inventory by item and location
Record each stock item’s quantity on hand, where it is stored and its reorder point. Count fast-moving and high-value items more often than the rest.
3. Tag and count both
Barcode, QR and RFID labels make counting faster and cut typing mistakes. See how asset tags work and how teams run a full count with asset inventory software.
4. Reconcile to the ledger
Each month, match the register’s total cost and accumulated depreciation, and the inventory valuation, to the general ledger. Explain every difference while it is still fresh.
5. Maintain the equipment you depend on
Fixed assets that are serviced on schedule last longer and break down less. Keep repair history on the asset’s record so the cost of keeping it is visible when you decide whether to replace it.
How Asset Infinity Handles Fixed Assets and Spare Parts
Asset Infinity is built for the assets a business keeps and maintains, and for the spare parts that maintenance uses. It is not a system for inventory held for sale.
- Fixed asset register. Each asset has a number from a series you control, a category, site and location, custodian, purchase cost and dates. Statuses run from Planned and Operational to Retired and Disposed, and status history is kept. See fixed asset management software.
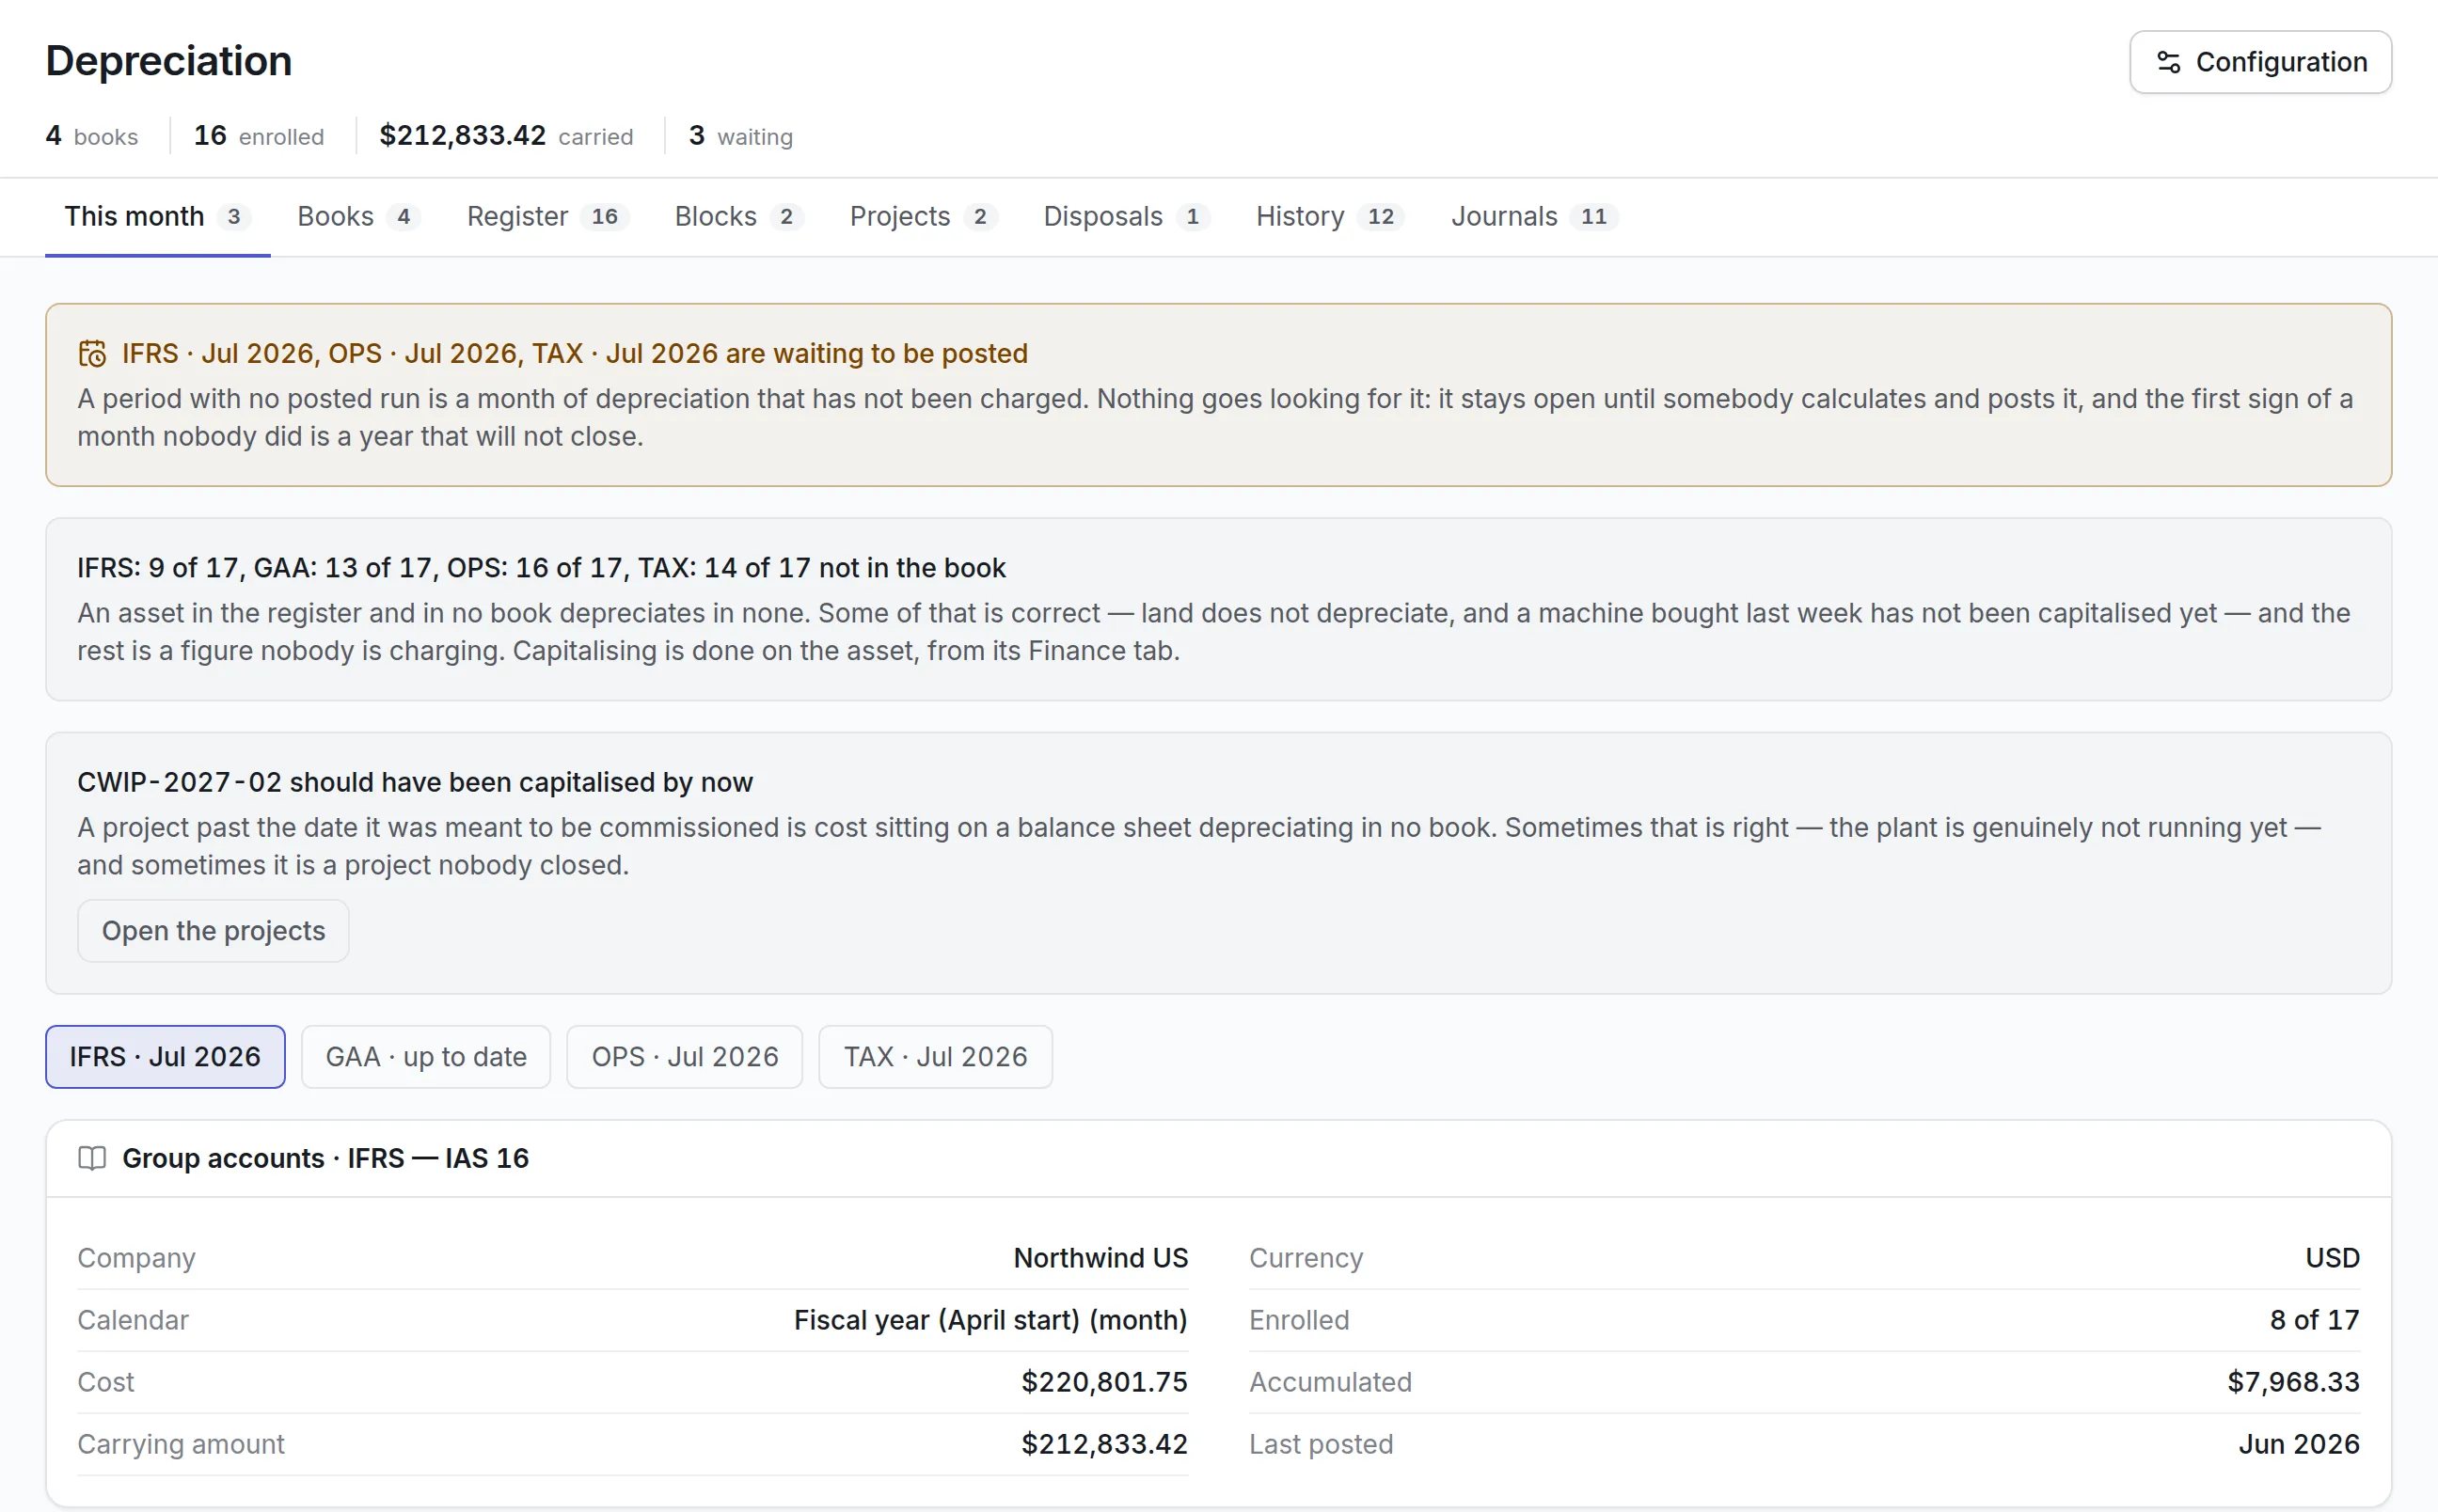
- Depreciation. Straight-line, declining balance, units of production driven by meter readings, and rate tables such as MACRS, in more than one book per asset. Runs are calculated, posted and can be reversed, and journals export to the general ledger.
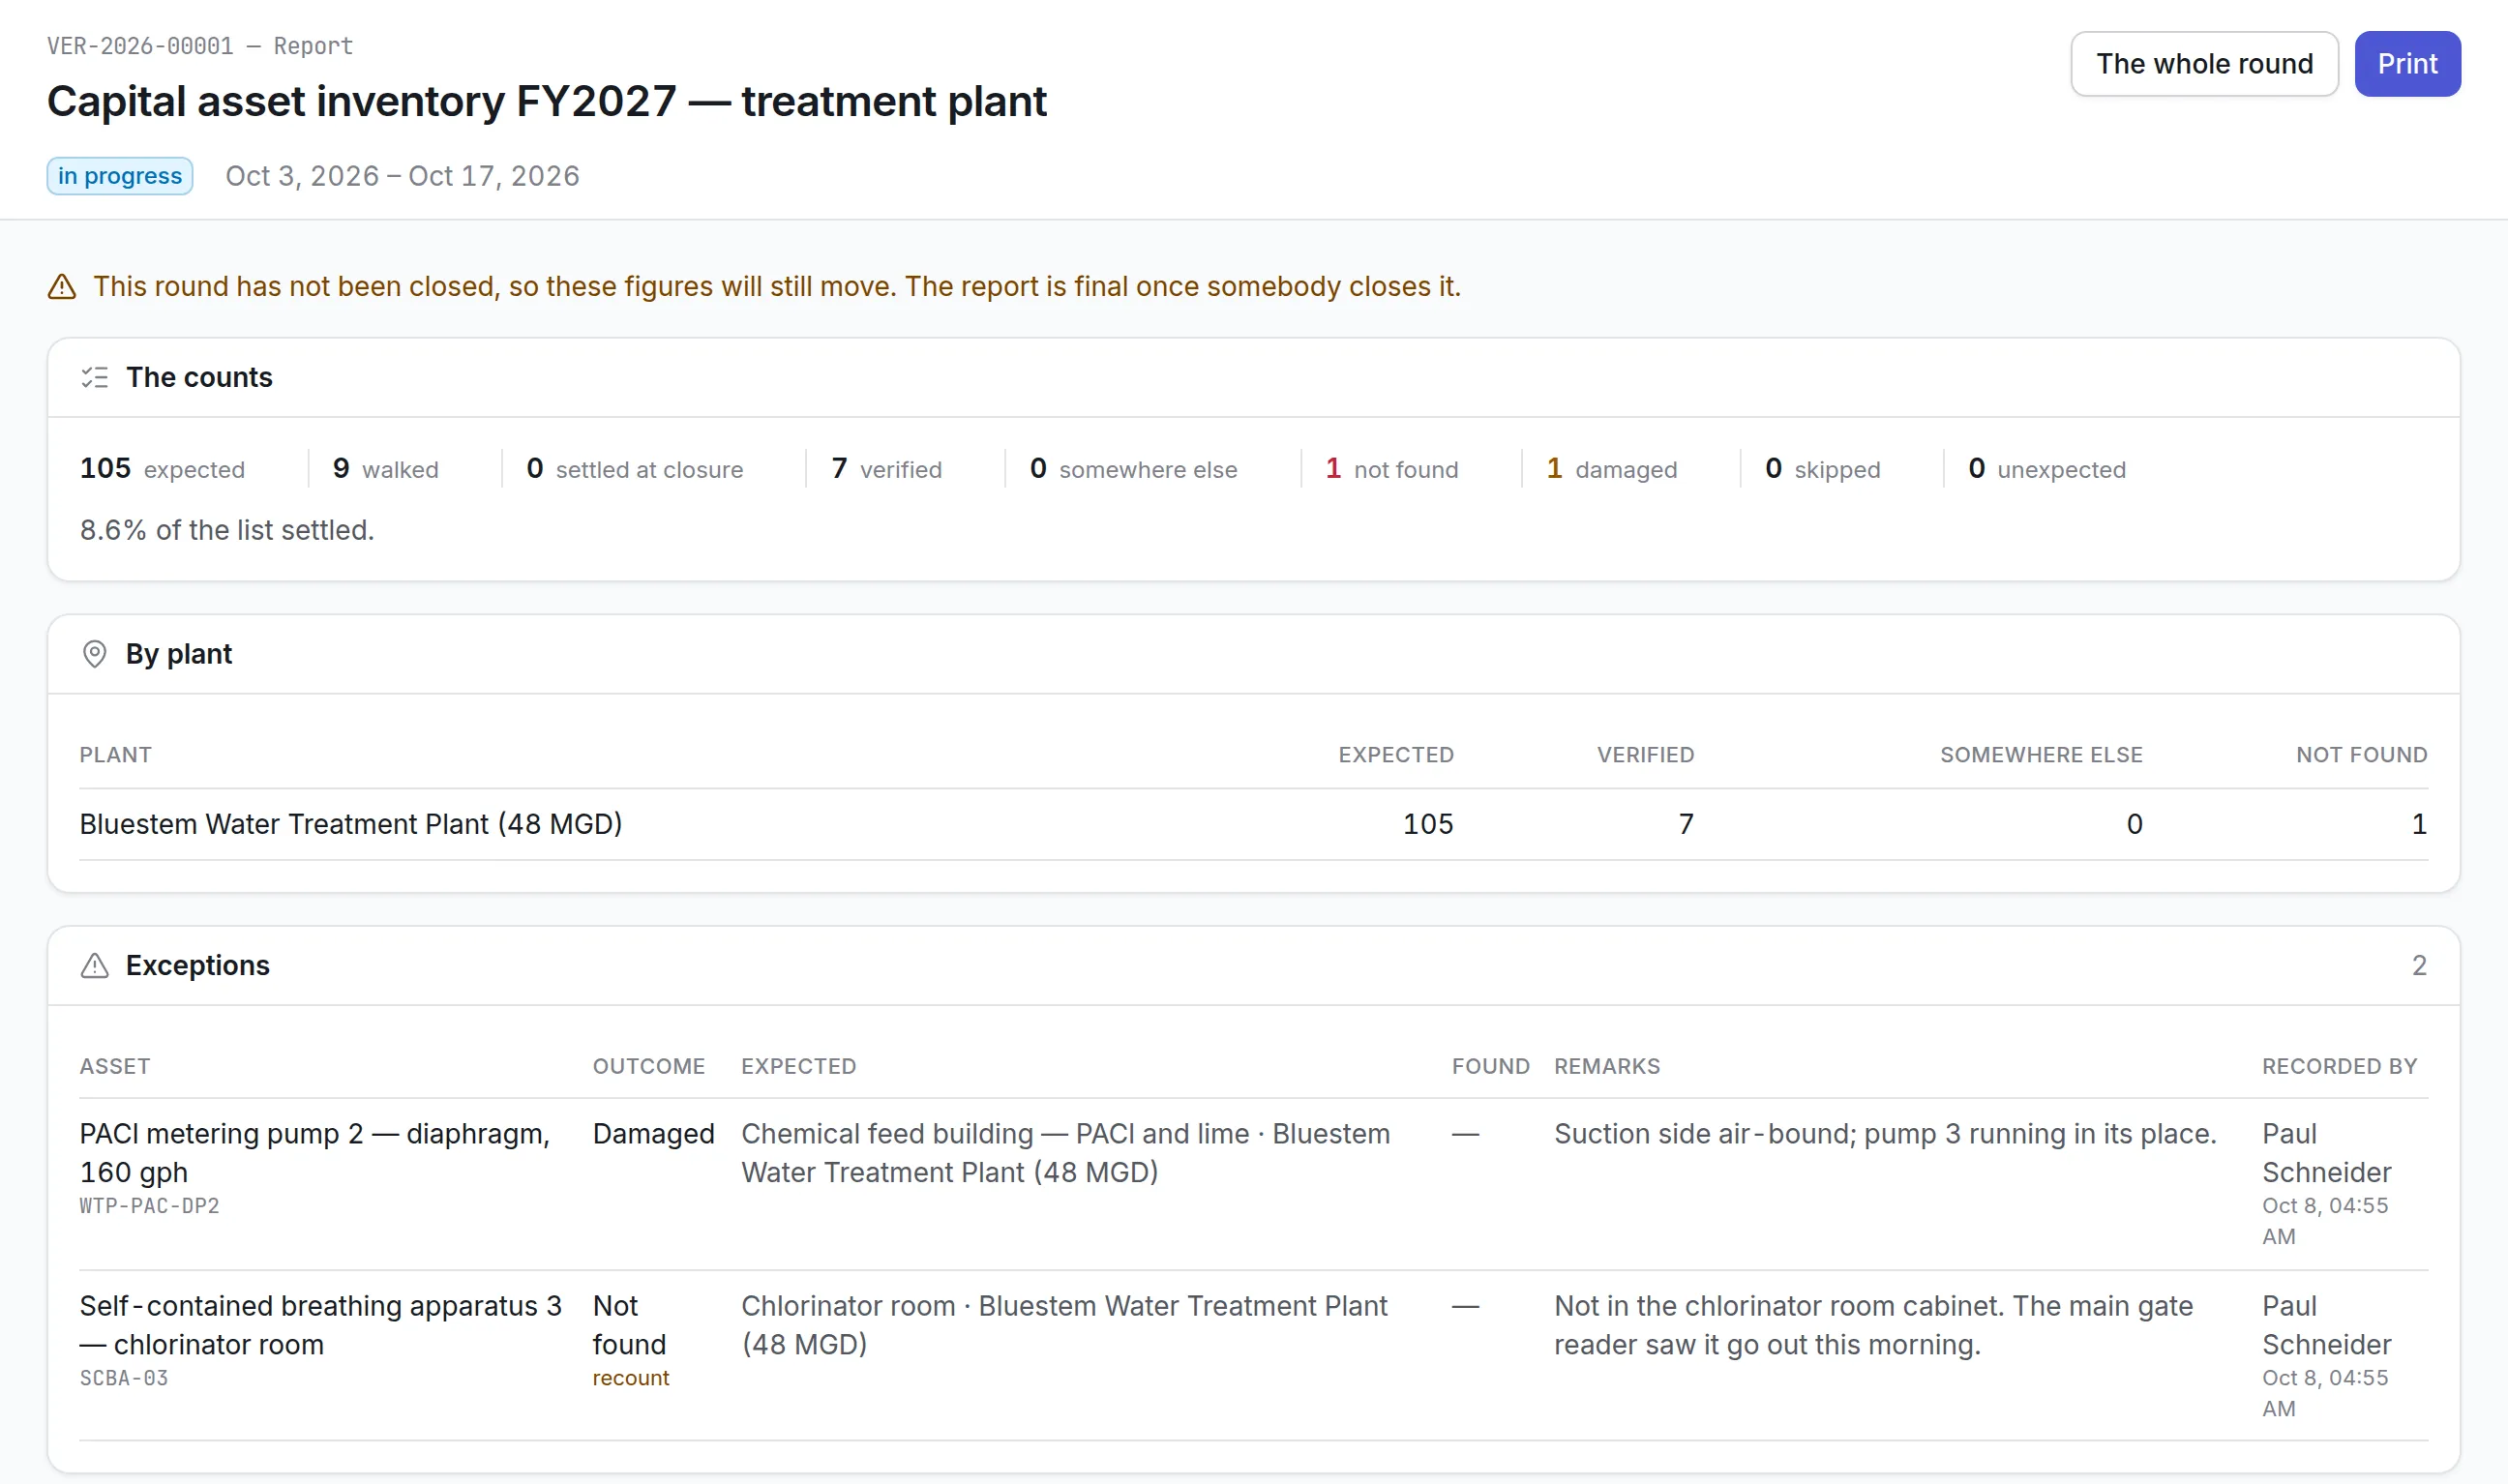
- Verification. Counts are done by scanning tags with the mobile app, and each asset is marked verified, moved, damaged or not found.
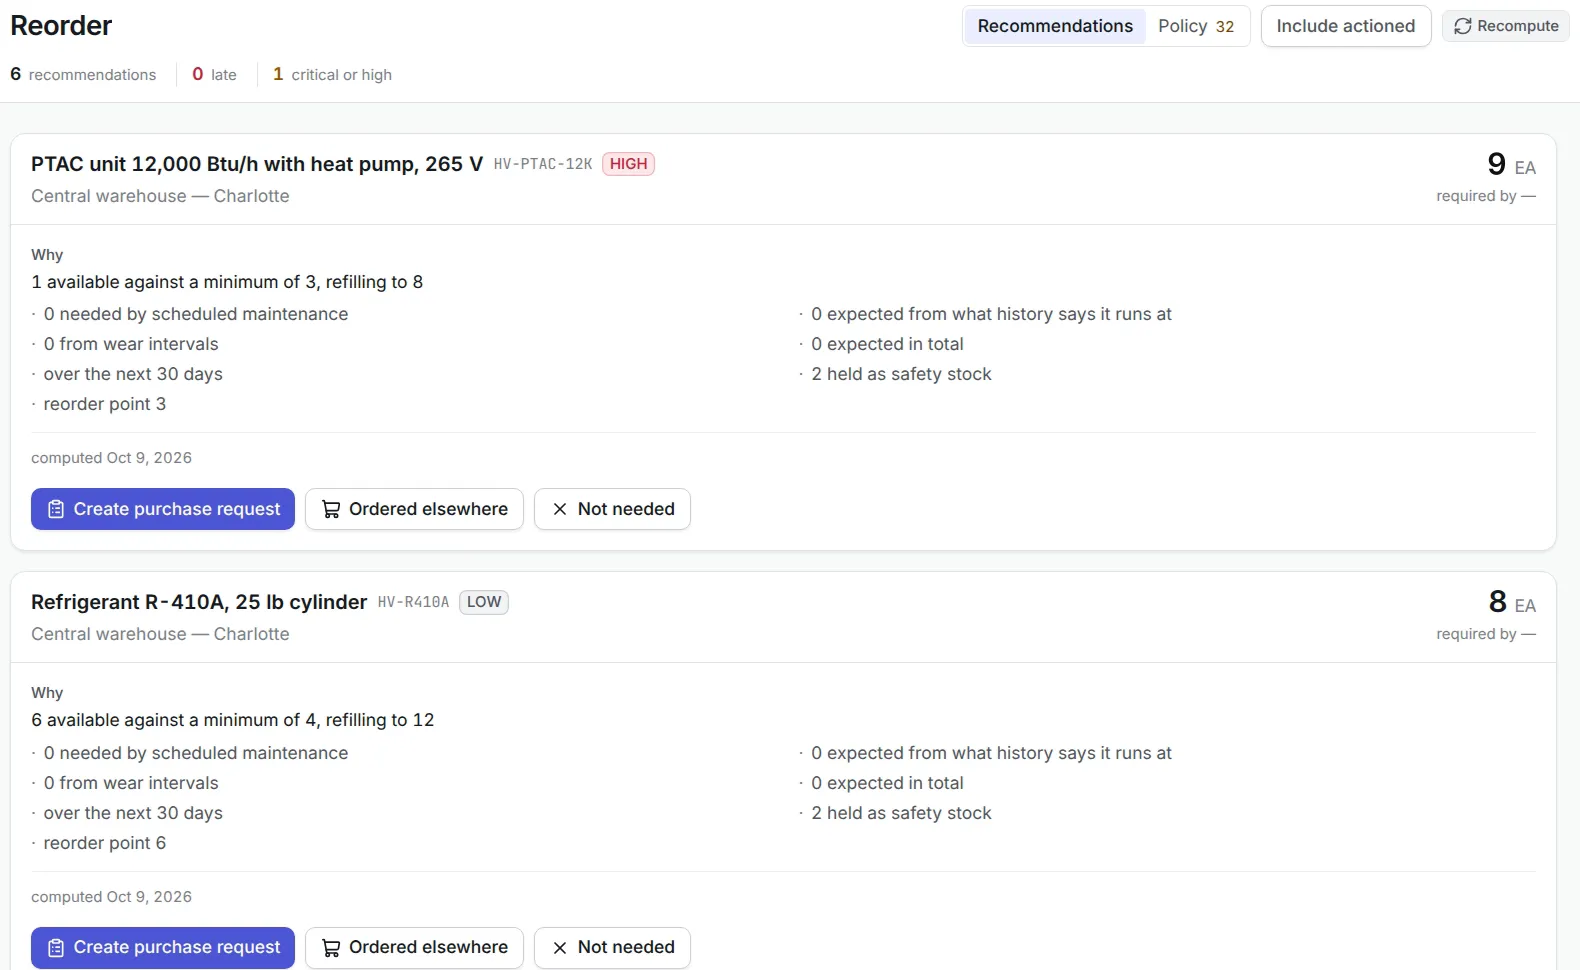
- Spare parts. Parts inventory management tracks spares by store, with on hand, reserved, available and on order quantities, and recommends what to reorder.
- Disposals. A disposal records the reason, buyer, sale price and the gain or loss for each book.
FAQs on Assets and Inventory
What is the difference between assets and liabilities?
Assets are resources a business owns that are expected to bring future benefit. Liabilities are amounts it owes to others. Assets minus liabilities equals equity.
Is inventory ever not an asset?
Inventory is always an asset while the business owns it. It stops being one when it is sold (its cost moves to cost of goods sold) or when it is written off because it is damaged, lost or obsolete.
How are assets and inventory valued?
Fixed assets are carried at cost less accumulated depreciation and any impairment. Inventory is carried at cost, reduced to net realizable value (or market, for LIFO and the retail method) when it is worth less than it cost.
What are some common examples of assets and inventory?
Fixed assets include machinery, vehicles, buildings and computers. Inventory includes raw materials, work in process and finished goods. Cash and accounts receivable are current assets that are neither.
Are spare parts inventory or fixed assets?
Routine spare parts and supplies are usually carried as inventory or expensed when used. Major spare parts or standby equipment that will be used over more than one year with a specific machine are often capitalized as property, plant and equipment.