

Asset reconciliation is the work of making three things agree: the assets physically on your sites, the asset register that lists them, and the fixed asset balances in your general ledger. When they agree, an auditor can pick any machine on the floor and find it in the books, and pick any line in the books and be shown the machine.
They rarely agree on their own. Equipment moves without anyone updating the record, assets are scrapped without a disposal entry, and new purchases are expensed when they should have been capitalized. This guide explains what asset reconciliation is, how it differs from asset verification, the fixed asset reconciliation process step by step, a worked example, and the usual causes of differences with the fix for each.
What Is Asset Reconciliation?
Asset reconciliation is the process of comparing an organization’s asset records with physical reality and with the general ledger, then investigating and correcting every difference. It confirms that each recorded asset exists, is where the record says, and is valued correctly, and that the register totals for cost and accumulated depreciation equal the ledger balances.
For example, if the register says the Chicago office holds 10 laptops and a count finds 8, the two missing laptops need an explanation: moved, disposed of, or lost. Each answer leads to a different correction in the register and, if the asset is gone, in the ledger.
Asset Verification vs Asset Reconciliation
The two terms are often used together, and they are two halves of one job. Asset verification checks that assets physically exist. Asset reconciliation compares those results, and the ledger, with the records and fixes the differences.
| Asset verification | Asset reconciliation | |
|---|---|---|
| Question it answers | Is the asset here, and in what condition? | Do the floor, the register and the ledger agree? |
| How it is done | A physical count: scanning labels or reading tags | Comparing lists and balances, then investigating |
| Who usually does it | Operations, facilities or auditors on site | Finance, with input from site teams |
| Output | Each asset marked found, moved, damaged or not found | Corrected register, adjusting entries and an explanation for each difference |
| How often | Yearly, or more often for portable assets | Ledger match every month; full match after each count |
The physical asset verification checklist covers how to plan and run the count itself.
The Two Directions of Fixed Asset Reconciliation
Fixed asset reconciliation works in two directions, and both are needed.
| Direction | Compares | Catches |
|---|---|---|
| Physical to register | The count results with the asset register | Missing, moved, damaged and unrecorded assets |
| Register to ledger | Register totals with general ledger balances | Unposted depreciation, unrecorded disposals, additions posted to the wrong account |
Auditors test both. They pick assets from the register and ask to see them, they pick assets on the floor and ask to see them in the register, and they check that the register total equals the ledger.
The Asset Reconciliation Process in Seven Steps
- Fix the scope and the cut-off date. Decide which sites and asset classes are included, and freeze the register list as at a date, so everyone counts against the same list.
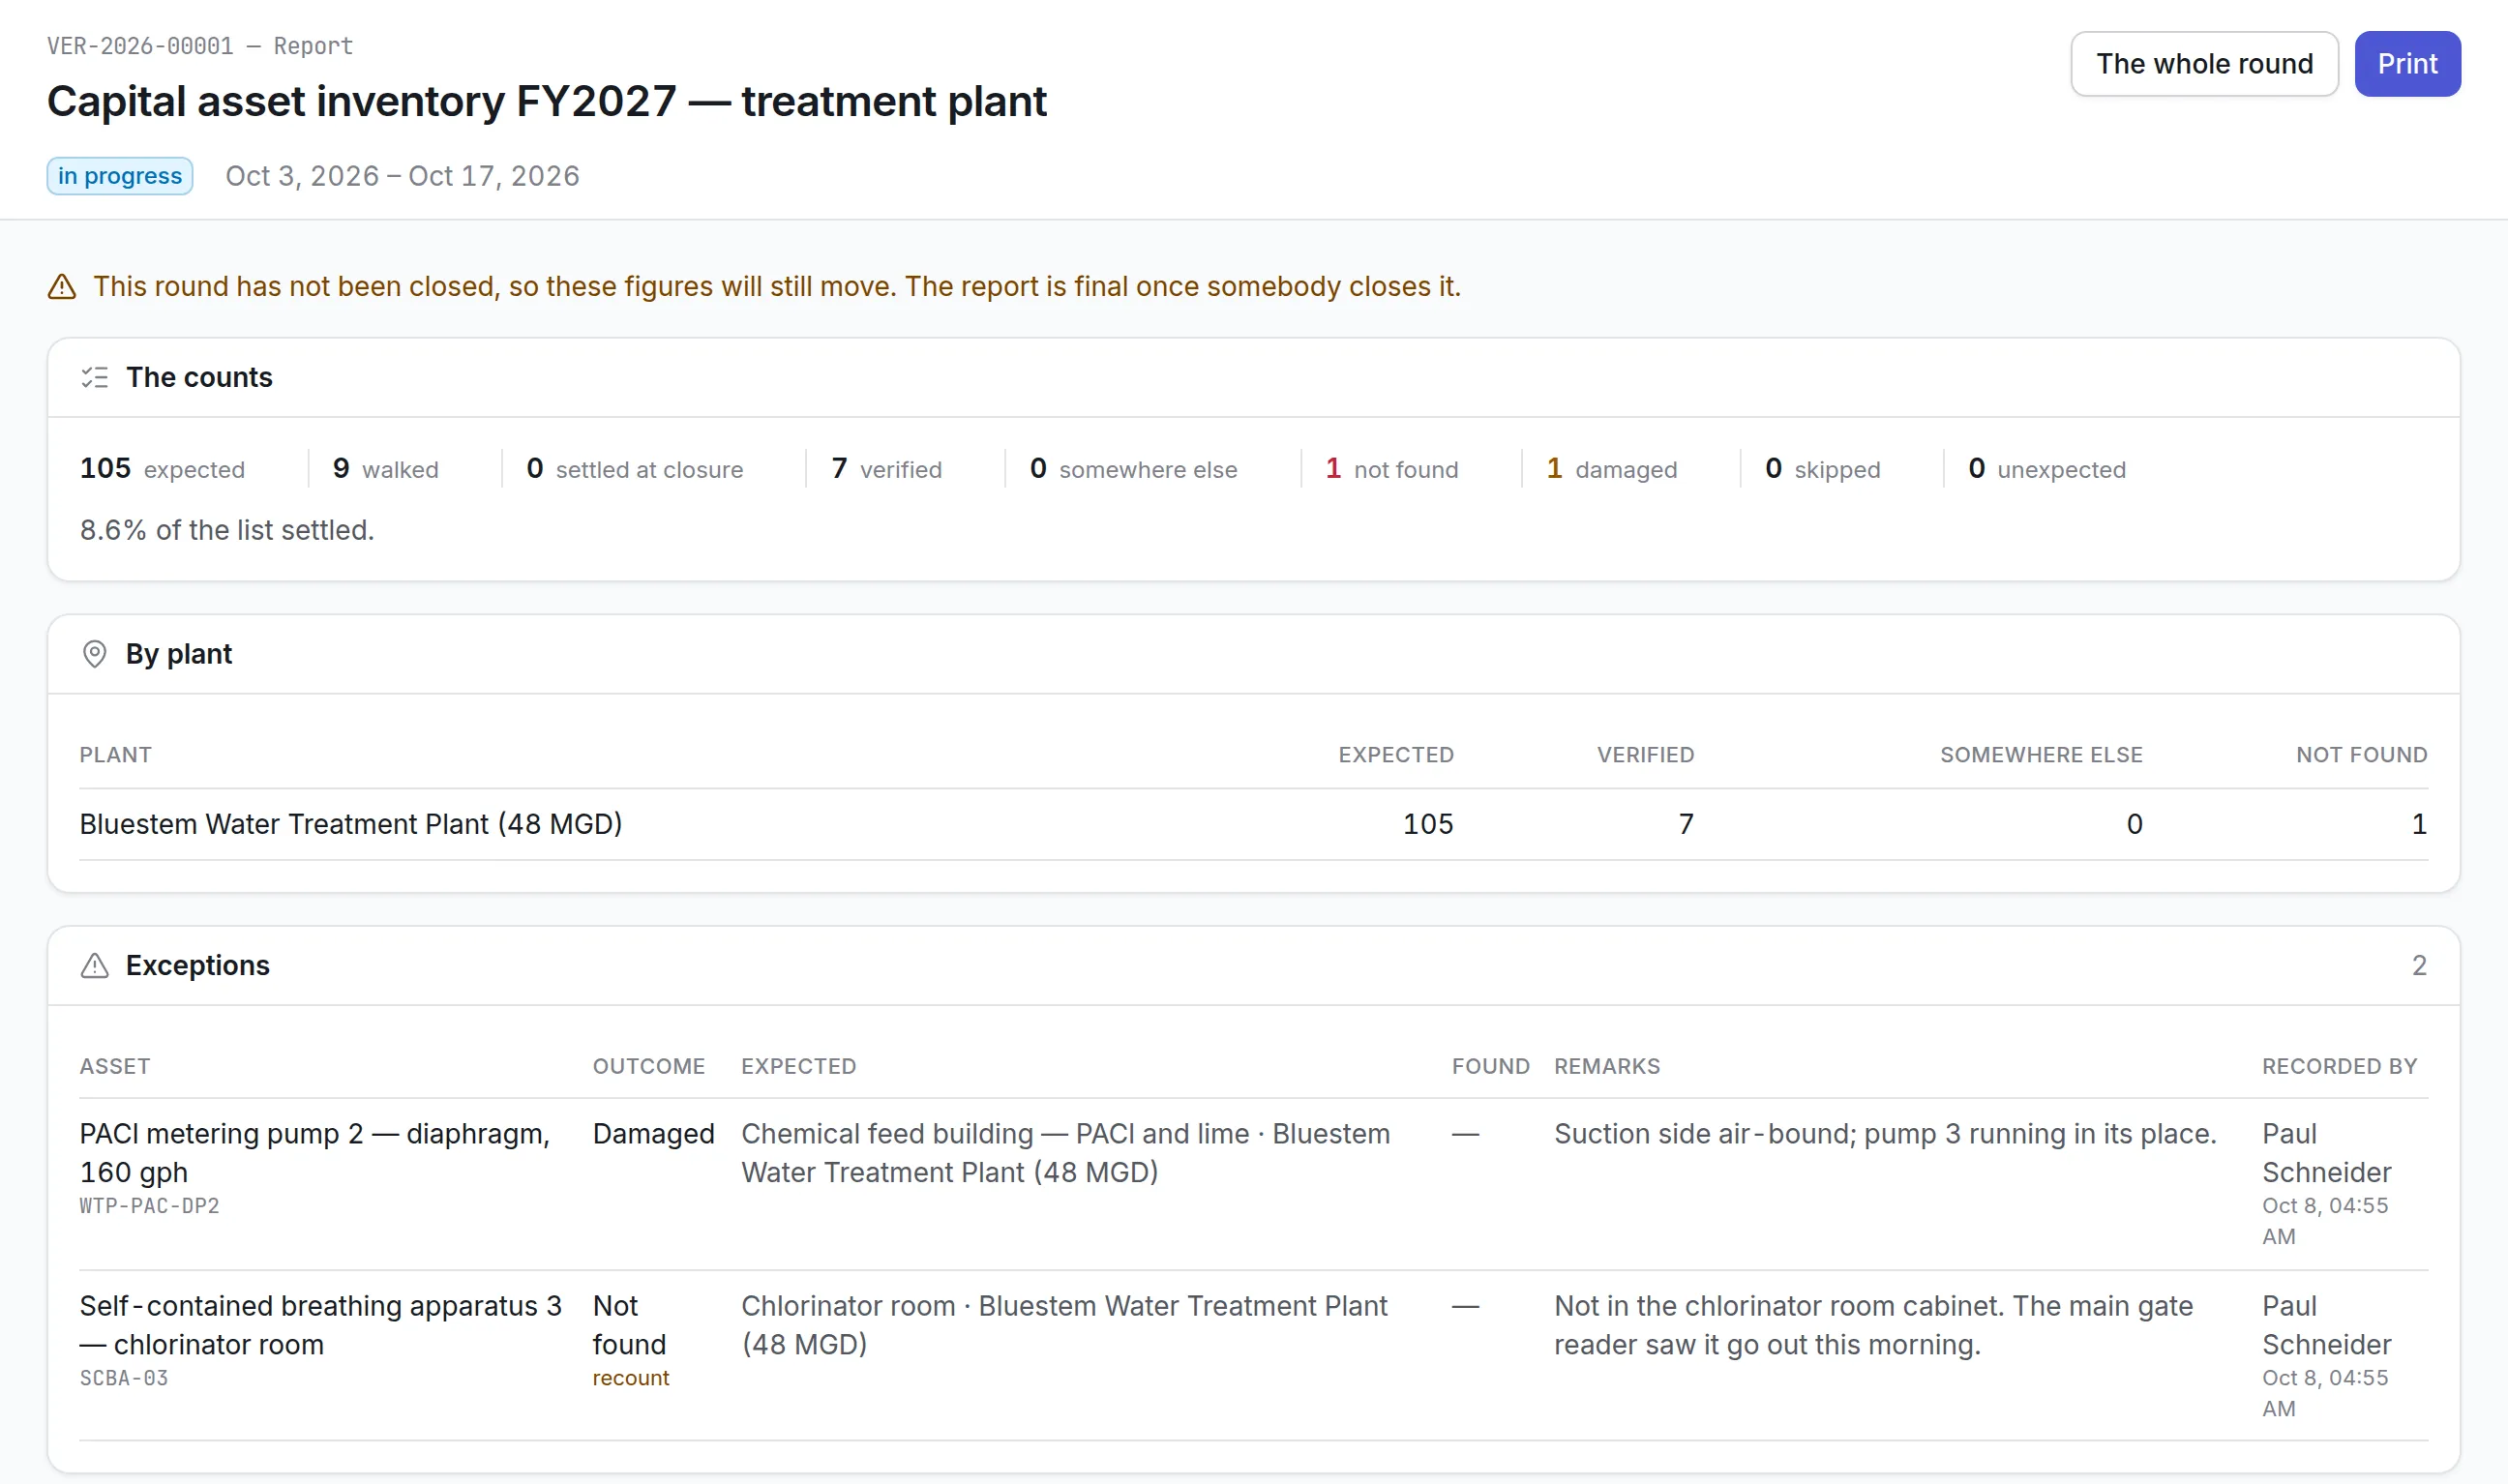
- Count the assets. Scan every label at each location and record each asset as found, moved, damaged or not found. Record anything found that is not on the list.
- Match the count to the register. Every register line should have a count result, and every item found should have a register line.
- Match the register to the ledger. Total the register’s cost and accumulated depreciation by asset class and compare them with the ledger accounts.
- Investigate each difference. Check transfer records, disposal paperwork, purchase invoices and maintenance history before deciding what happened.
- Correct the records. Update locations and custodians, record disposals and write-offs, add unrecorded assets, and post adjusting entries in the ledger.
- Report and sign off. Summarize what was counted, what differed, what was corrected and what remains open, and have the owner sign it.
Fixed Asset Reconciliation Example
Here is a fixed assets reconciliation for one asset class, computer equipment, at the end of a quarter. The ledger shows a cost of $412,600 and the register totals $398,200, a difference of $14,400.
| Item | Amount | Explanation |
|---|---|---|
| General ledger cost, computer equipment | $412,600 | Balance at quarter end |
| Less: servers disposed of in March, not recorded in the ledger | ($9,800) | Disposal recorded in the register but never posted |
| Less: printer posted to computer equipment in error | ($2,100) | Belongs to office equipment |
| Less: duplicate invoice posting for a laptop | ($2,500) | Same invoice entered twice |
| Adjusted ledger cost | $398,200 | |
| Asset register cost, computer equipment | $398,200 | Total of register lines |
| Difference after adjustment | $0 |
The physical count found two more issues the ledger could not show: one laptop recorded at the Chicago office was in Denver (a location correction, no ledger effect), and one monitor could not be found (a write-off after investigation, with its net book value posted as a loss).
Common Causes of Differences and How to Fix Each
| Difference | Likely cause | Fix |
|---|---|---|
| Asset on the register, not found | Moved, scrapped without a record, lost or stolen | Check transfers and disposals; if gone, record the disposal or write-off |
| Asset found, not on the register | Bought and expensed, received but never recorded, or a personal item | Check the invoice and the capitalization policy; add it or exclude it |
| Asset found in the wrong place | A move nobody recorded | Update location and custodian |
| Register total differs from the ledger | Unposted depreciation or disposal, or a posting to the wrong account | Post the missing entry or reclassify |
| Same asset listed twice | Re-entered after a transfer or a re-tag | Merge the records and keep the history |
| Ghost assets on the books | Disposals never recorded over several years | Write them off after investigation; see ghost assets |
How Often to Reconcile Fixed Assets
Most organizations reconcile the register to the ledger every month, as part of the close, because a difference found in the month it happened takes minutes to explain. A full physical count with reconciliation is done at least once a year. Portable, high-value assets such as laptops, tools and test equipment are often counted quarterly, and a sample count between full counts catches drift early.
A reconciliation is also worth running after any event that changes many records at once: a site closure, a merger, a move to new software, or a large disposal.
How Asset Infinity Handles Verification and Reconciliation
Asset Infinity’s asset inventory software runs counts as verification rounds, and the asset register holds the records they check.
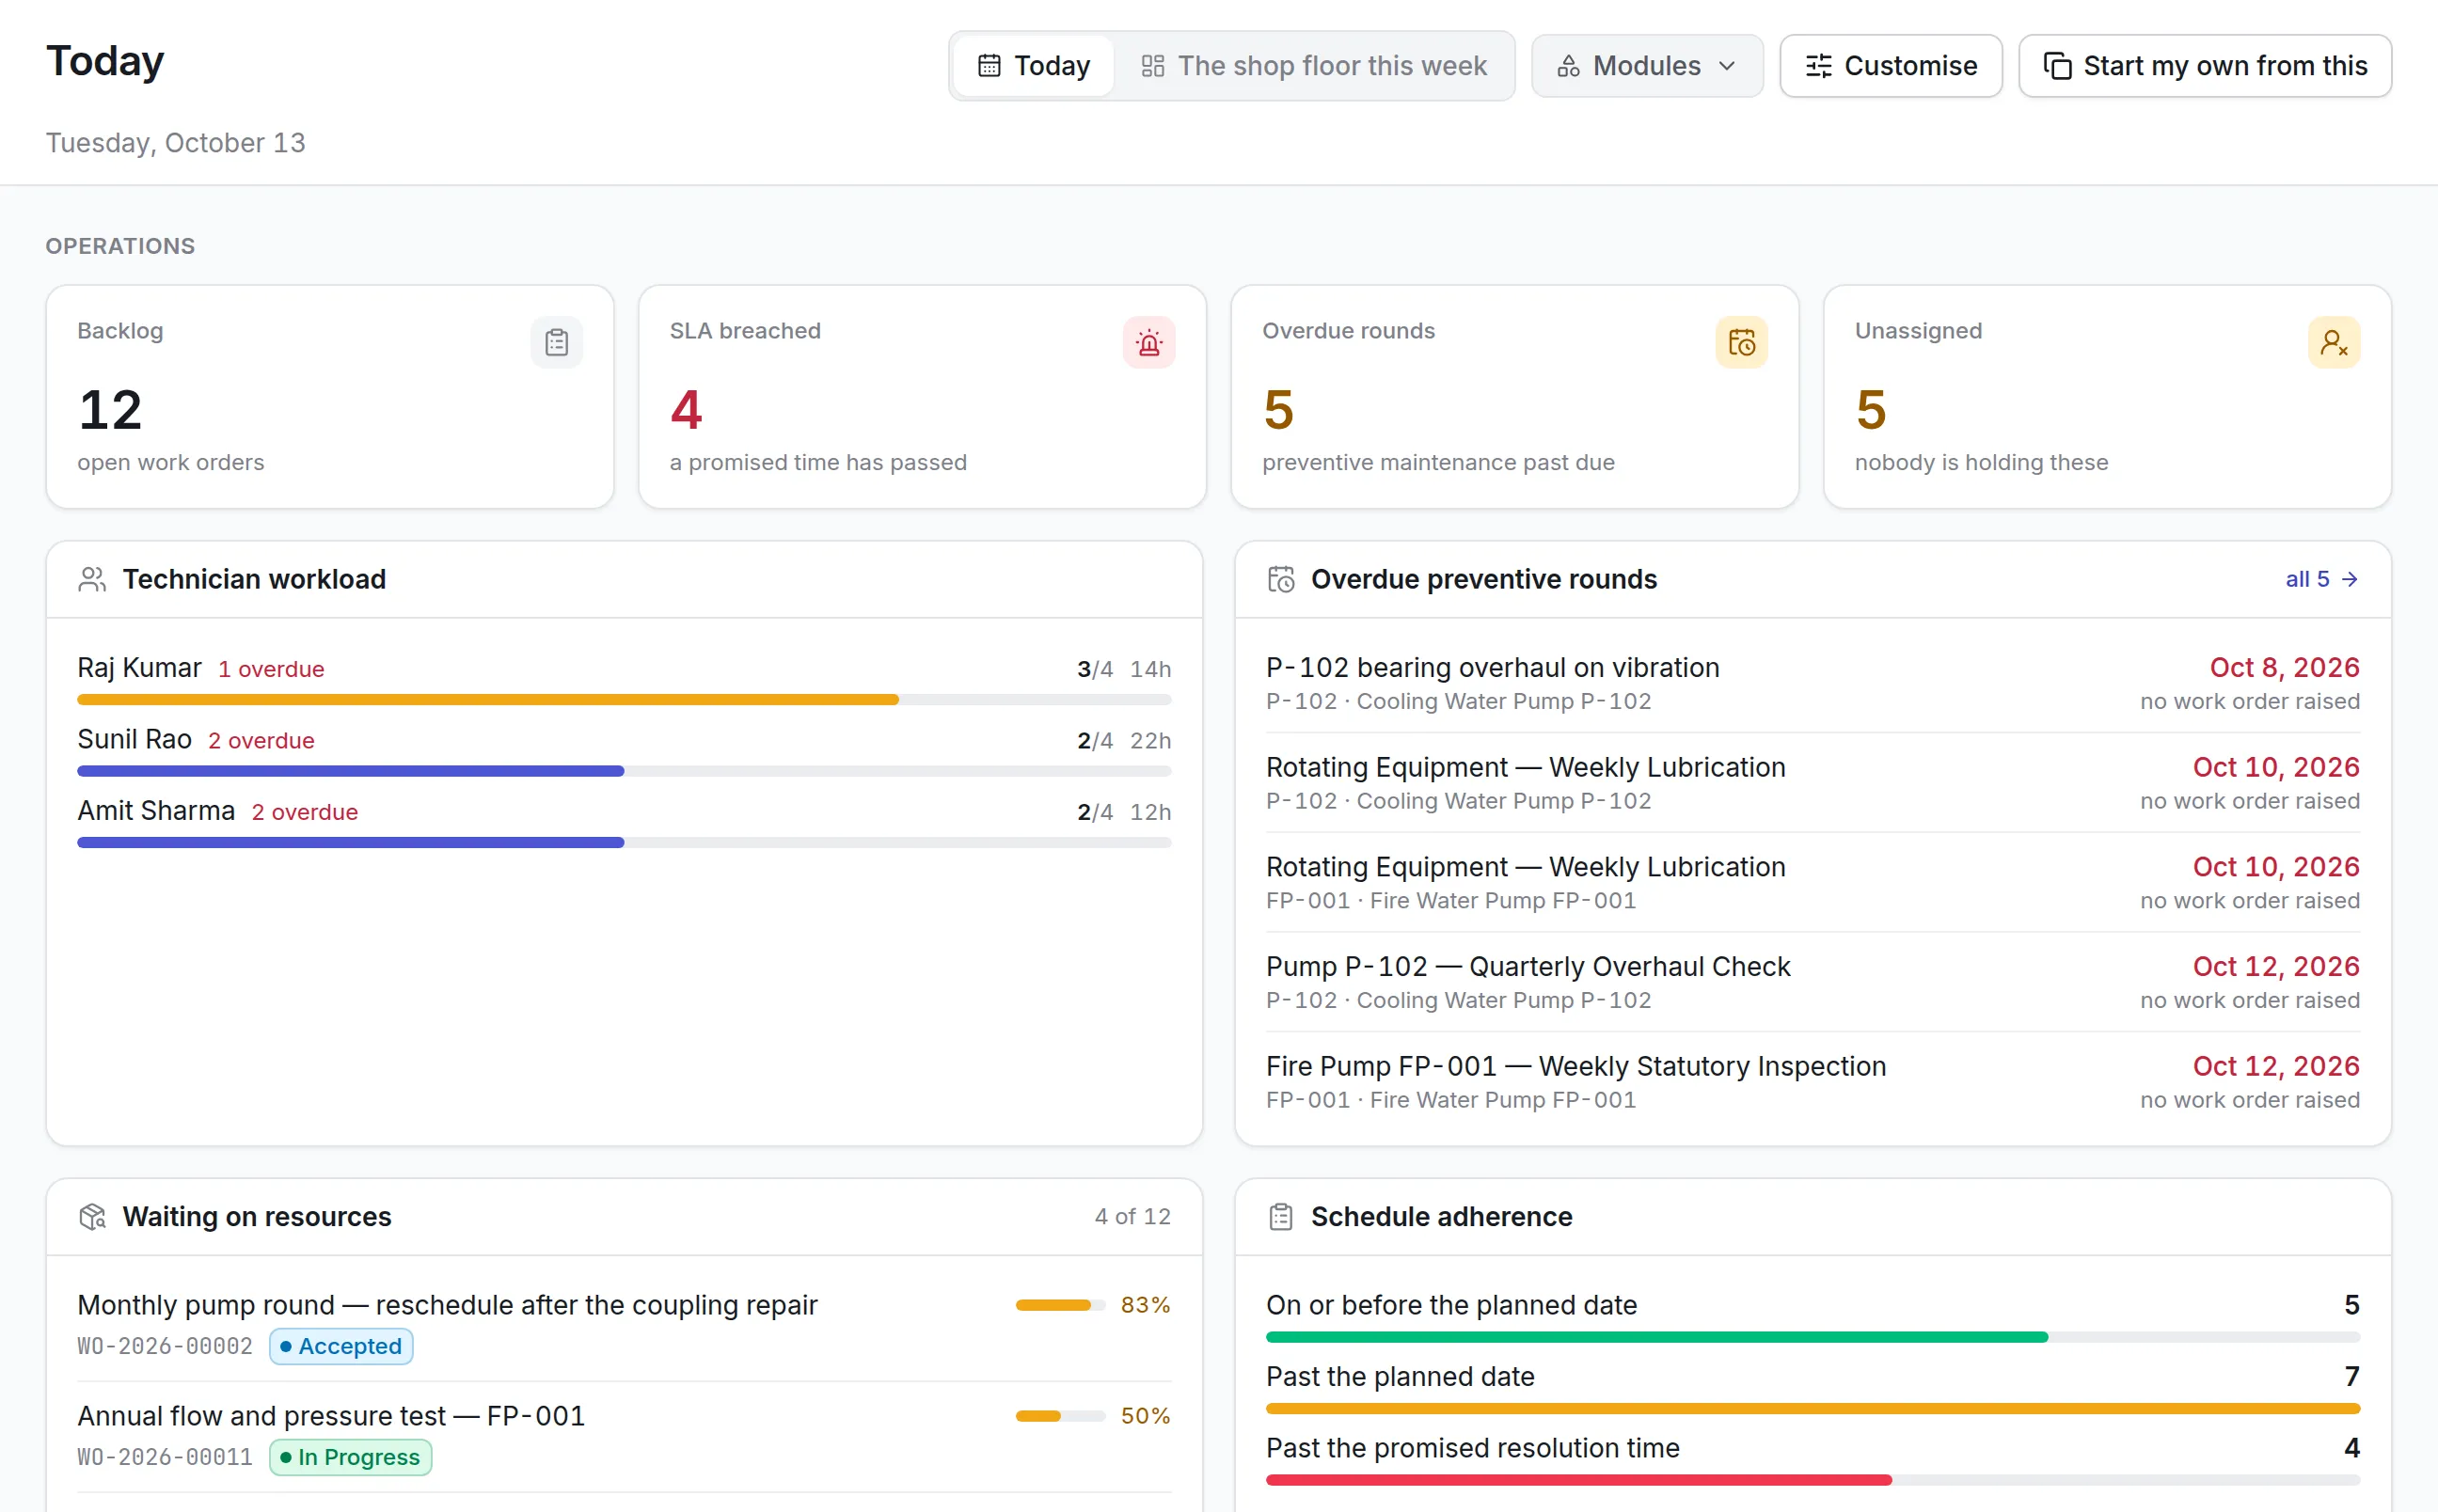
- Four kinds of round. Full, sample, targeted (such as a recount of last year’s missing items) and self-verification, where custodians confirm what they hold.
- Counted on a phone. Auditors scan asset tags with the mobile app and record each asset as verified, moved, not found, damaged or skipped, with its condition as good, fair, poor or unserviceable.
- Disposals with reasons. Sold, scrapped, lost, donated or transferred, with buyer, reference, sale price and the gain or loss per book.
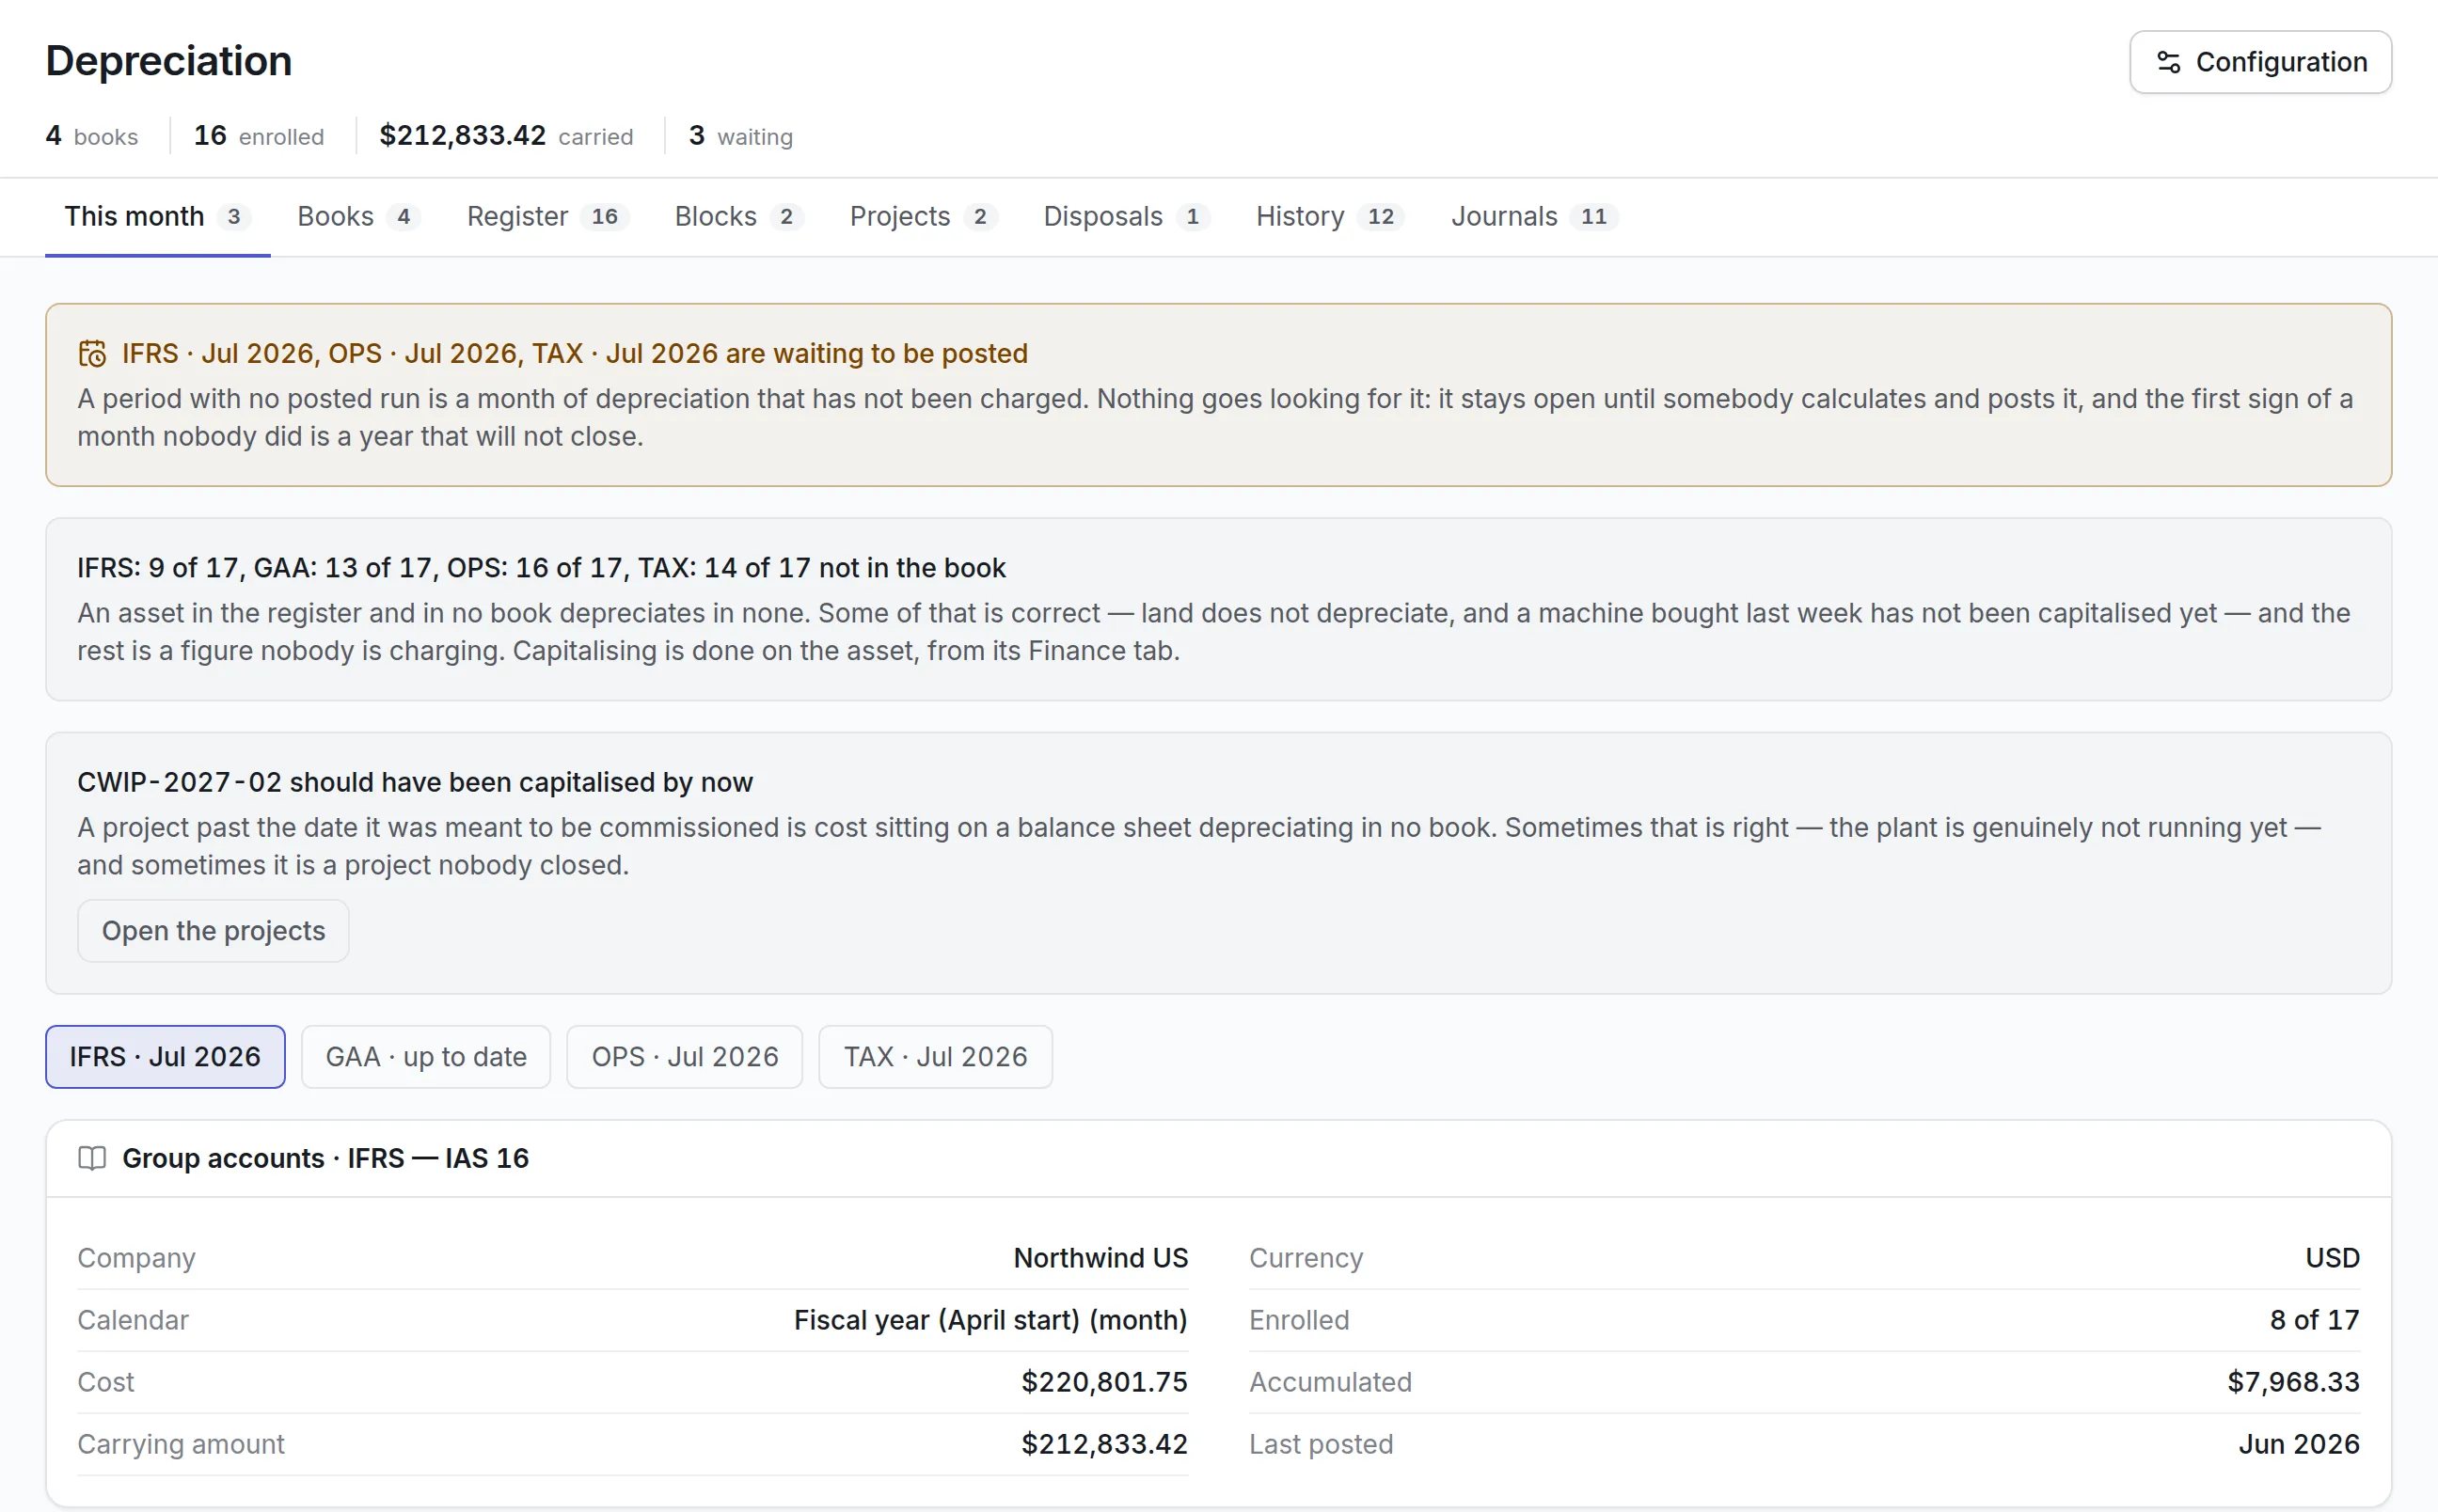
- Depreciation tied to the ledger. Runs are calculated, posted and can be reversed, and journals export to the general ledger.
- Reports to reconcile from. Asset verification results, verification round summary, depreciation register, book value by asset class and disposals by reason are standard reports.
- An audit trail on every record, so each correction shows who made it and when.
For the accounting side in more depth, read the fixed asset reconciliation guide.
Frequently Asked Questions
What is the difference between asset reconciliation and asset verification?
Asset verification physically checks that each asset exists and where it is. Asset reconciliation compares those results and the ledger with the register, then investigates and corrects every difference.
What is fixed asset reconciliation?
Fixed asset reconciliation matches the fixed asset register to the physical assets and to the general ledger balances for cost and accumulated depreciation. Differences are investigated and corrected with register updates and adjusting entries.
How often should fixed assets be reconciled?
Reconcile the register to the ledger monthly, and run a full physical count with reconciliation at least once a year. Count portable, high-value assets more often.
What happens to an asset that cannot be found?
It is investigated first, using transfer, disposal and maintenance records. If it is confirmed gone, it is written off: removed from the register, with its remaining book value posted as a loss.
Can asset reconciliation help prevent fraud?
Yes. Regular counts and reconciliations make missing assets visible quickly, and an audit trail shows who changed each record, which discourages misuse and false entries.