

A fixed asset audit procedure is the set of checks that proves the buildings, machinery, vehicles and equipment in your books exist, are where the register says, are valued correctly and still belong to the business. Fixed assets are often the largest number on the balance sheet, so an internal audit of them catches differences before an external auditor, a lender or a tax authority does.
This guide covers what an internal audit of fixed assets is for, the seven-step procedure, a checklist you can work from, how to prepare the organization, the findings that come up most often and how to run the physical count with a phone instead of a printout.
What Is a Fixed Asset Audit?
A fixed asset audit is a review that compares the fixed asset register with the assets on the floor and with the general ledger. It confirms each recorded asset exists, is in the stated location and condition, is owned by the business, and is carried at the right cost, depreciation and net book value. It also looks for assets that are missing from the register.
An internal audit is run by the business itself, usually finance with help from operations. An external audit is run by an independent firm as part of the financial statement audit. The procedure is much the same; the difference is who signs the report. A business that runs its own audit of fixed assets during the year gives the external auditor a clean register to test.
Why Fixed Asset Audits Are Essential
Without regular audits, registers drift. Assets are moved without a record, scrapped without being written off, or bought and never added. Each gap leads to a real cost:
- Ghost assets stay on the books after they are gone, so the balance sheet is overstated and you keep paying insurance and property tax on them.
- Unrecorded assets are not insured, not depreciated and not maintained on schedule.
- Wrong depreciation misstates profit and the tax return.
- Fraud goes unnoticed, such as equipment taken home, an asset sold below value with the proceeds never recorded, or a purchase booked at a higher cost than was paid.
A regular audit validates the existence and status of assets, supports compliance with accounting standards such as US GAAP, and reduces the room for fraud.
Key Objectives of a Fixed Asset Internal Audit
Auditors describe what they test as assertions. Each objective below maps to one of them.
| Objective | Assertion | What the auditor checks |
|---|---|---|
| Verify asset existence | Existence | Pick assets from the register and find them on the floor |
| Find unrecorded assets | Completeness | Pick assets on the floor and find them in the register; review recent purchases |
| Validate financial records | Valuation | Cost, useful life, depreciation method and net book value are right and match the ledger |
| Confirm ownership | Rights and obligations | Invoices, titles and lease agreements show the business owns or controls the asset |
| Assess asset condition | Valuation | Damaged or idle assets may need an impairment review or disposal |
| Review compliance | Presentation and disclosure | Capitalization policy, disposals and classes follow your policy and accounting standards |
| Evaluate asset utilization | Operational | Idle or underused assets that could be moved, sold or retired |
The first two objectives need a physical count. The rest are document and ledger work, which is why an audit is easier when the register already holds purchase documents, disposal records and a history of every change.
Step-by-Step Internal Audit Procedure for Fixed Assets
The internal audit procedure for fixed assets runs in seven steps. Plan for the count to take the most time, and for the follow-up to decide whether the next audit is any easier.
- Plan the audit. Define the scope (sites, asset classes, a value threshold), the objectives and the dates. Identify high-risk areas such as portable equipment, recent additions, assets at remote sites and anything with a history of differences. Collect the register, purchase orders, invoices, the depreciation schedule and last year’s findings.
- Choose full or sample. A full count covers every asset in scope. A sample count picks a random share, or targets high-value and high-risk items. Many businesses count everything once a year and sample in between.
- Conduct physical verification. Walk each location with the list and confirm each asset by its tag or serial number. Record the location, condition and custodian, and note anything found that is not on the list. Barcode, QR or RFID tags make this a scan instead of a search.
- Review asset valuations. Check that additions are recorded at cost, including freight, installation and taxes paid, and that useful lives and methods follow your policy. Recalculate depreciation for a sample. Confirm disposals were removed with the gain or loss posted.
- Assess maintenance records. Confirm critical equipment was serviced on schedule. Poor condition or missed service can mean a shorter useful life or an impairment.
- Analyze compliance and document findings. Compare results with your capitalization policy, internal controls and tax rules. List every difference with its evidence: not found, found elsewhere, damaged, not on the register, valued wrongly. Report to management with a recommended fix for each.
- Implement corrective actions. Update locations, write off missing assets after investigation, add unrecorded ones, adjust depreciation, and dispose of obsolete equipment. Then reconcile the register to the general ledger again so the fixes are complete.
Fixed Asset Audit Procedure Checklist
Use this checklist to make sure no part of the fixed asset audit procedure is skipped.
| Area | Check | Done |
|---|---|---|
| Register | Every asset has a unique number, category, location, custodian and cost | ☐ |
| Ledger | Register totals for cost and accumulated depreciation equal the general ledger | ☐ |
| Additions | Each addition this year has an invoice and meets the capitalization threshold | ☐ |
| Disposals | Each disposal has a date, method, proceeds and posted gain or loss | ☐ |
| Count | Sample from register to floor and from floor to register | ☐ |
| Tags | Every counted asset carries a readable tag | ☐ |
| Depreciation | Methods and lives match policy; a sample is recalculated | ☐ |
| Condition | Damaged and idle assets are listed for impairment or disposal review | ☐ |
| Leased assets | Leased equipment is identified and kept apart from owned assets | ☐ |
| Sign-off | Findings, fixes and owners are recorded and approved | ☐ |
For the count itself, our physical asset verification checklist goes item by item, and the fixed asset reconciliation guide covers matching the register to the ledger.
How to Prepare Your Organization for an Asset Audit
A fruitful audit starts weeks before anyone walks the floor. These steps make it shorter for everyone:
- Set a deadline for each department. Ask for location changes, disposals and new purchases to be reported by a fixed date, so the register is current when the count starts.
- Keep an audit file. Hold purchase invoices, lease agreements, disposal approvals and loan documents that name assets in one place.
- Tag before you count. Label any untagged asset first. Counting untagged equipment means matching serial numbers by hand.
- Run smaller counts during the year. Quarterly sample counts of portable, high-value items mean the annual audit finds fewer surprises.
- Treat the auditor as a partner. An internal auditor who finds a process gap is saving you from the same finding in the external audit.
Classification also needs agreeing in advance. Whether an item is a fixed asset depends on the business: a truck is a fixed asset for a delivery company and inventory for the dealer selling it. Land is a fixed asset that is not depreciated.
Common Challenges in Fixed Asset Audits and How to Address Them
Incomplete Records
Assets bought on a credit card, received as part of a project or transferred from another site often never reach the register. Review purchase history for the period, and make adding an asset part of approving the invoice.
Discrepancies in Physical Verification
The register says a projector is in room 204 and it is in 310. Record it as found elsewhere, then update the location after the audit is checked. A count that rewrites the register as it goes makes mistakes impossible to trace.
Non-Compliance Issues
Assets below the capitalization threshold get capitalized, or disposals are never posted. Write the policy down, apply it at the point of purchase, and test a sample in every audit.
Time-Consuming Processes
A paper count means printing lists, ticking boxes and typing results back in. Scanning tags with a phone removes the printing and the retyping, and the results are ready when the last asset is scanned.
Identifying Idle or Obsolete Assets
An asset that exists but has not been used in a year passes an existence test and still costs money. Note condition and use during the count, and review idle assets with their owners.
Best Practices for Effective Fixed Asset Audits
- Audit on a schedule. A full count at least once a year, with sample counts in between for portable assets.
- Tag every asset. A durable label with a barcode, QR code or RFID chip makes every later count faster. See asset tags.
- Use one checklist. The same checklist every time means results can be compared year to year.
- Train the counters. People who count should know how to record found-elsewhere, damaged and not-found results the same way.
- Separate duties. The person who holds an asset should not be the only one who confirms it exists.
- Reconcile monthly. A register that matches the ledger every month leaves the audit with little to fix.
Benefits of Conducting Regular Internal Audits for Fixed Assets
Regular internal audits give the business accurate financial statements, because asset values reflect what is actually there. They reduce compliance risk and penalties, discourage fraud because people know assets are checked, and expose idle equipment that can be moved to where it is needed. They also extend asset life, because condition problems found during a count reach maintenance early.
Running the Fixed Asset Audit Procedure in Asset Infinity
Asset Infinity runs the count as a verification round on the same asset register your finance and maintenance teams use. The asset inventory software page has the full walkthrough; in short:
- Create a round. Choose full, sample, targeted or self-verification, and scope it by site, location, category, department or custodian. Publishing the round fixes the list, so an asset edited during the count cannot drop out of the total.
- Assign counters. Give each auditor a site or location so nothing is counted twice.
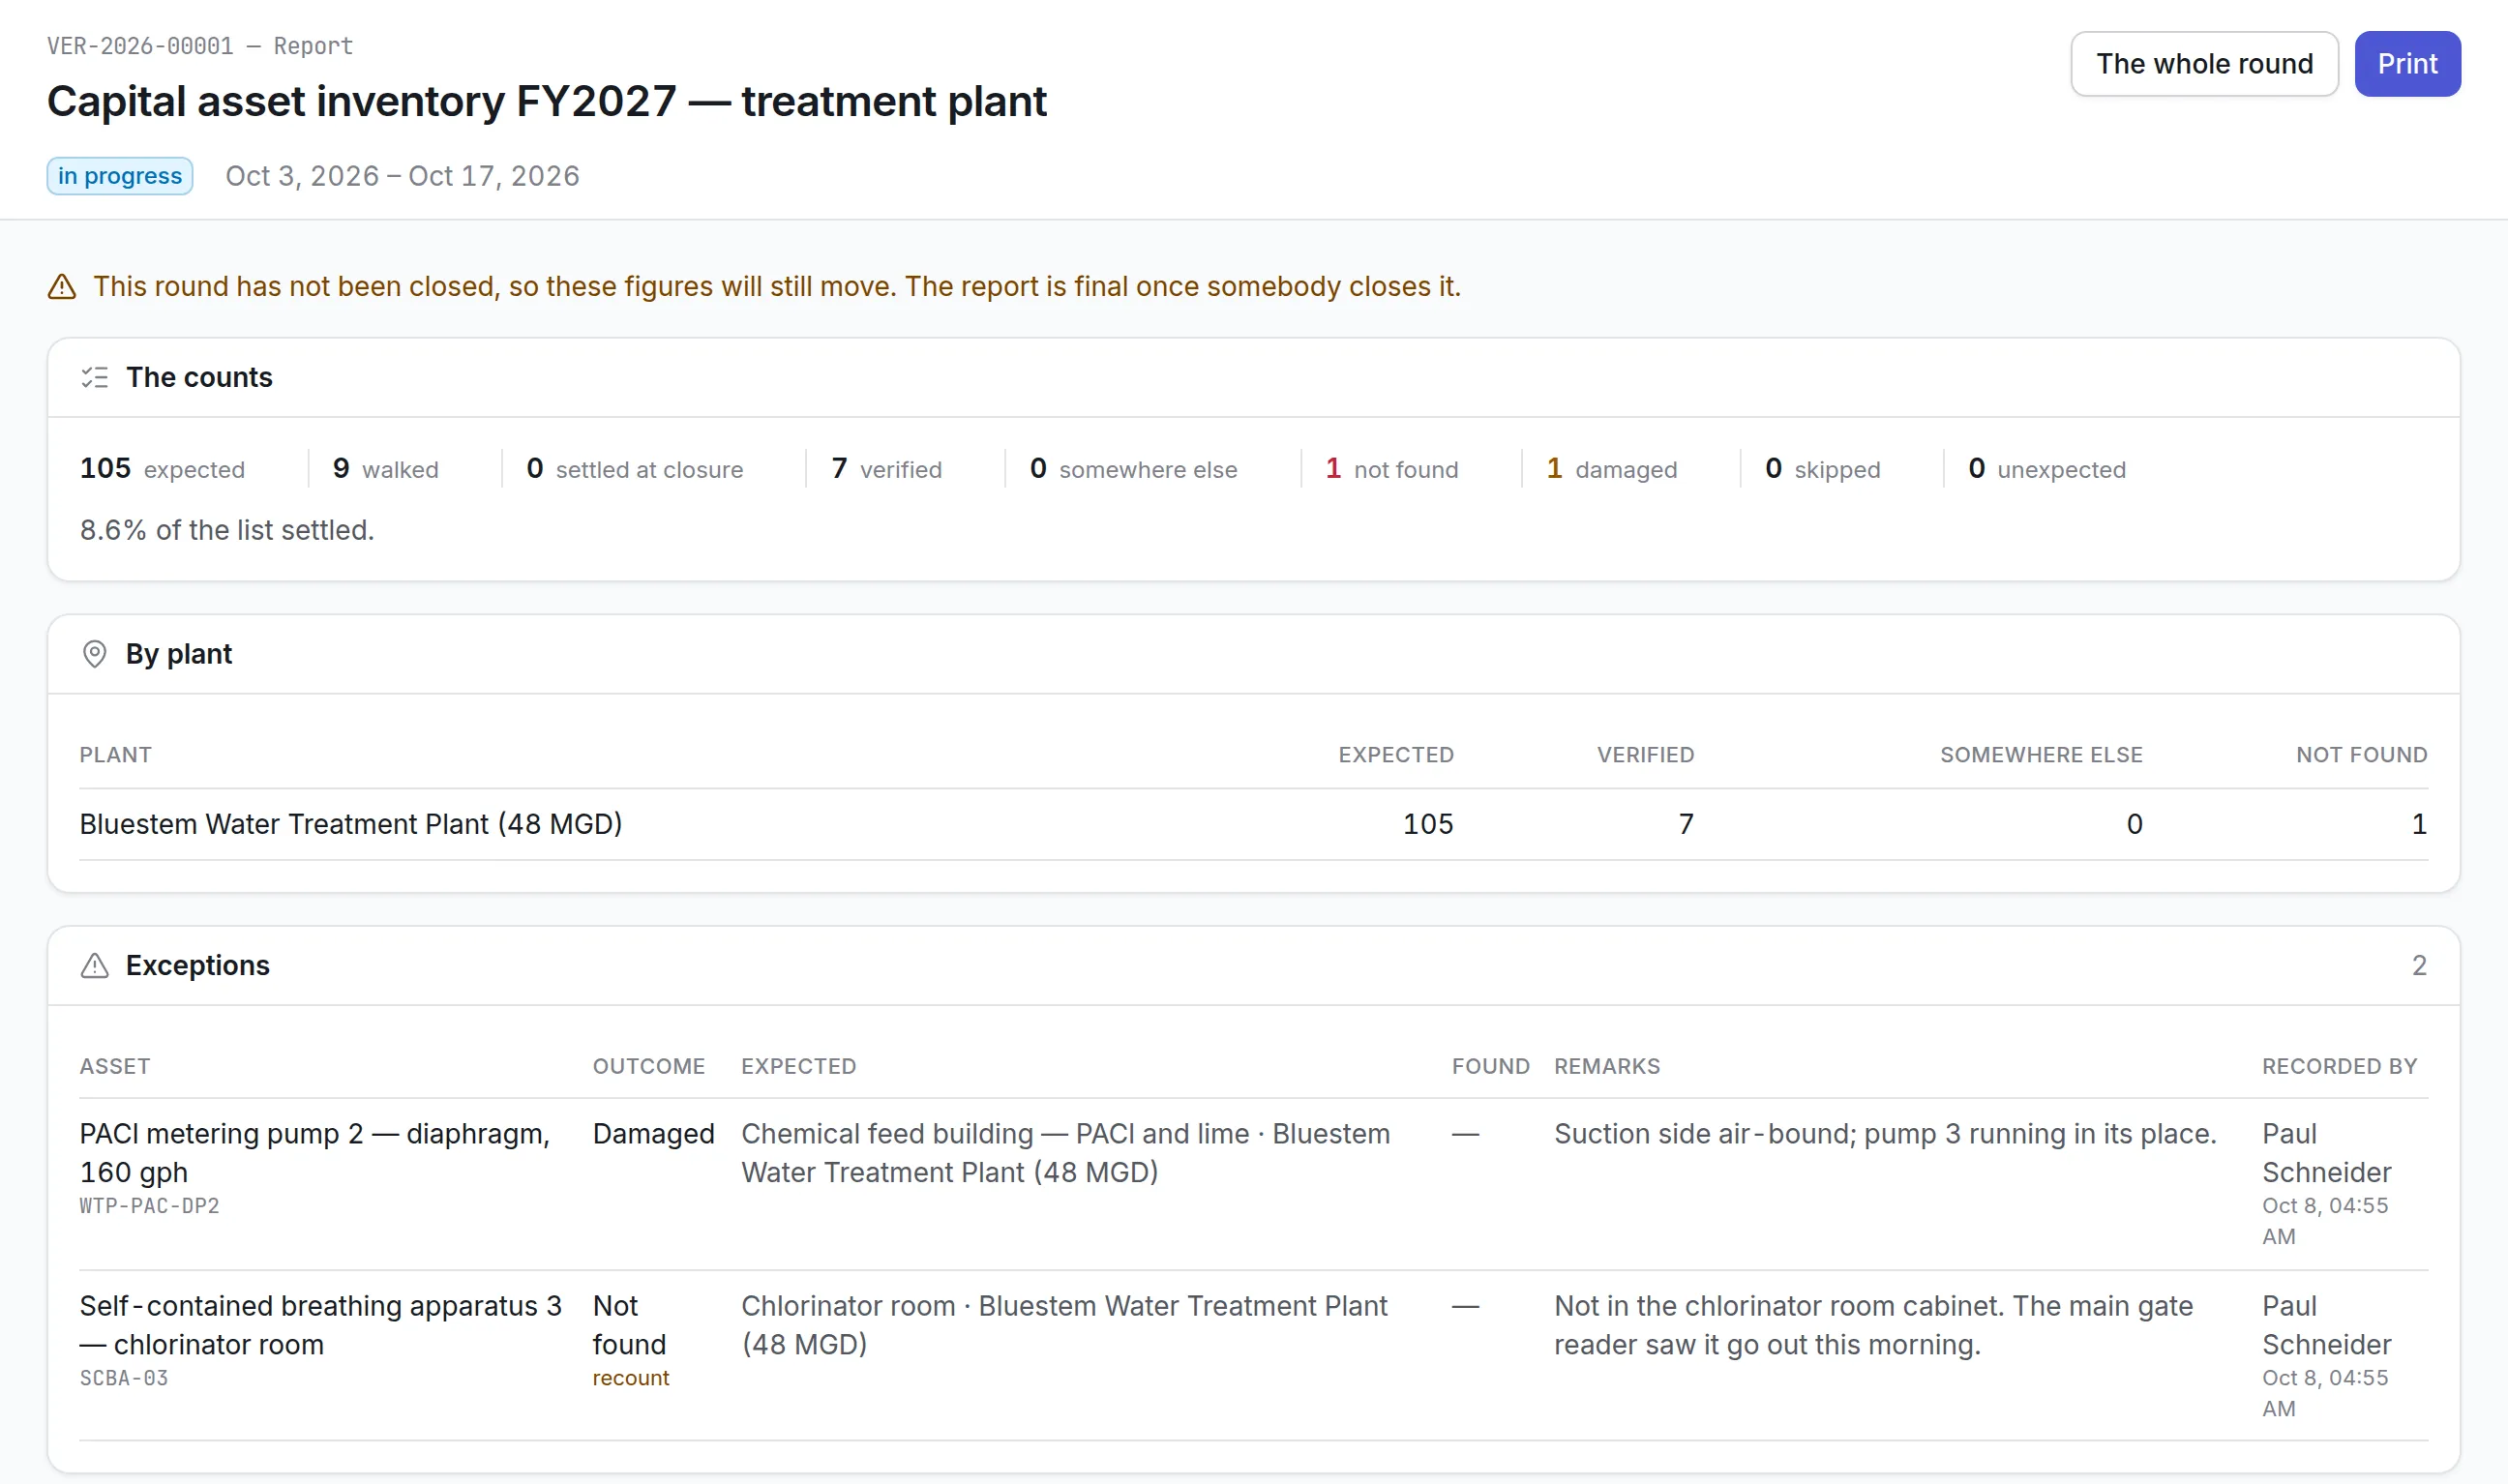
- Scan. Counters scan QR codes, barcodes or RFID tags in the mobile app, which keeps working without a signal. Each asset is recorded as verified, moved, not found, damaged or skipped, with a condition of good, fair, poor or unserviceable.
- Look again. A round can send every unfound asset back for a second look before it is recorded as missing.
- Close and report. The round report lists counts by site and every exception with who recorded it. An asset found elsewhere is moved in the register only when someone confirms it.
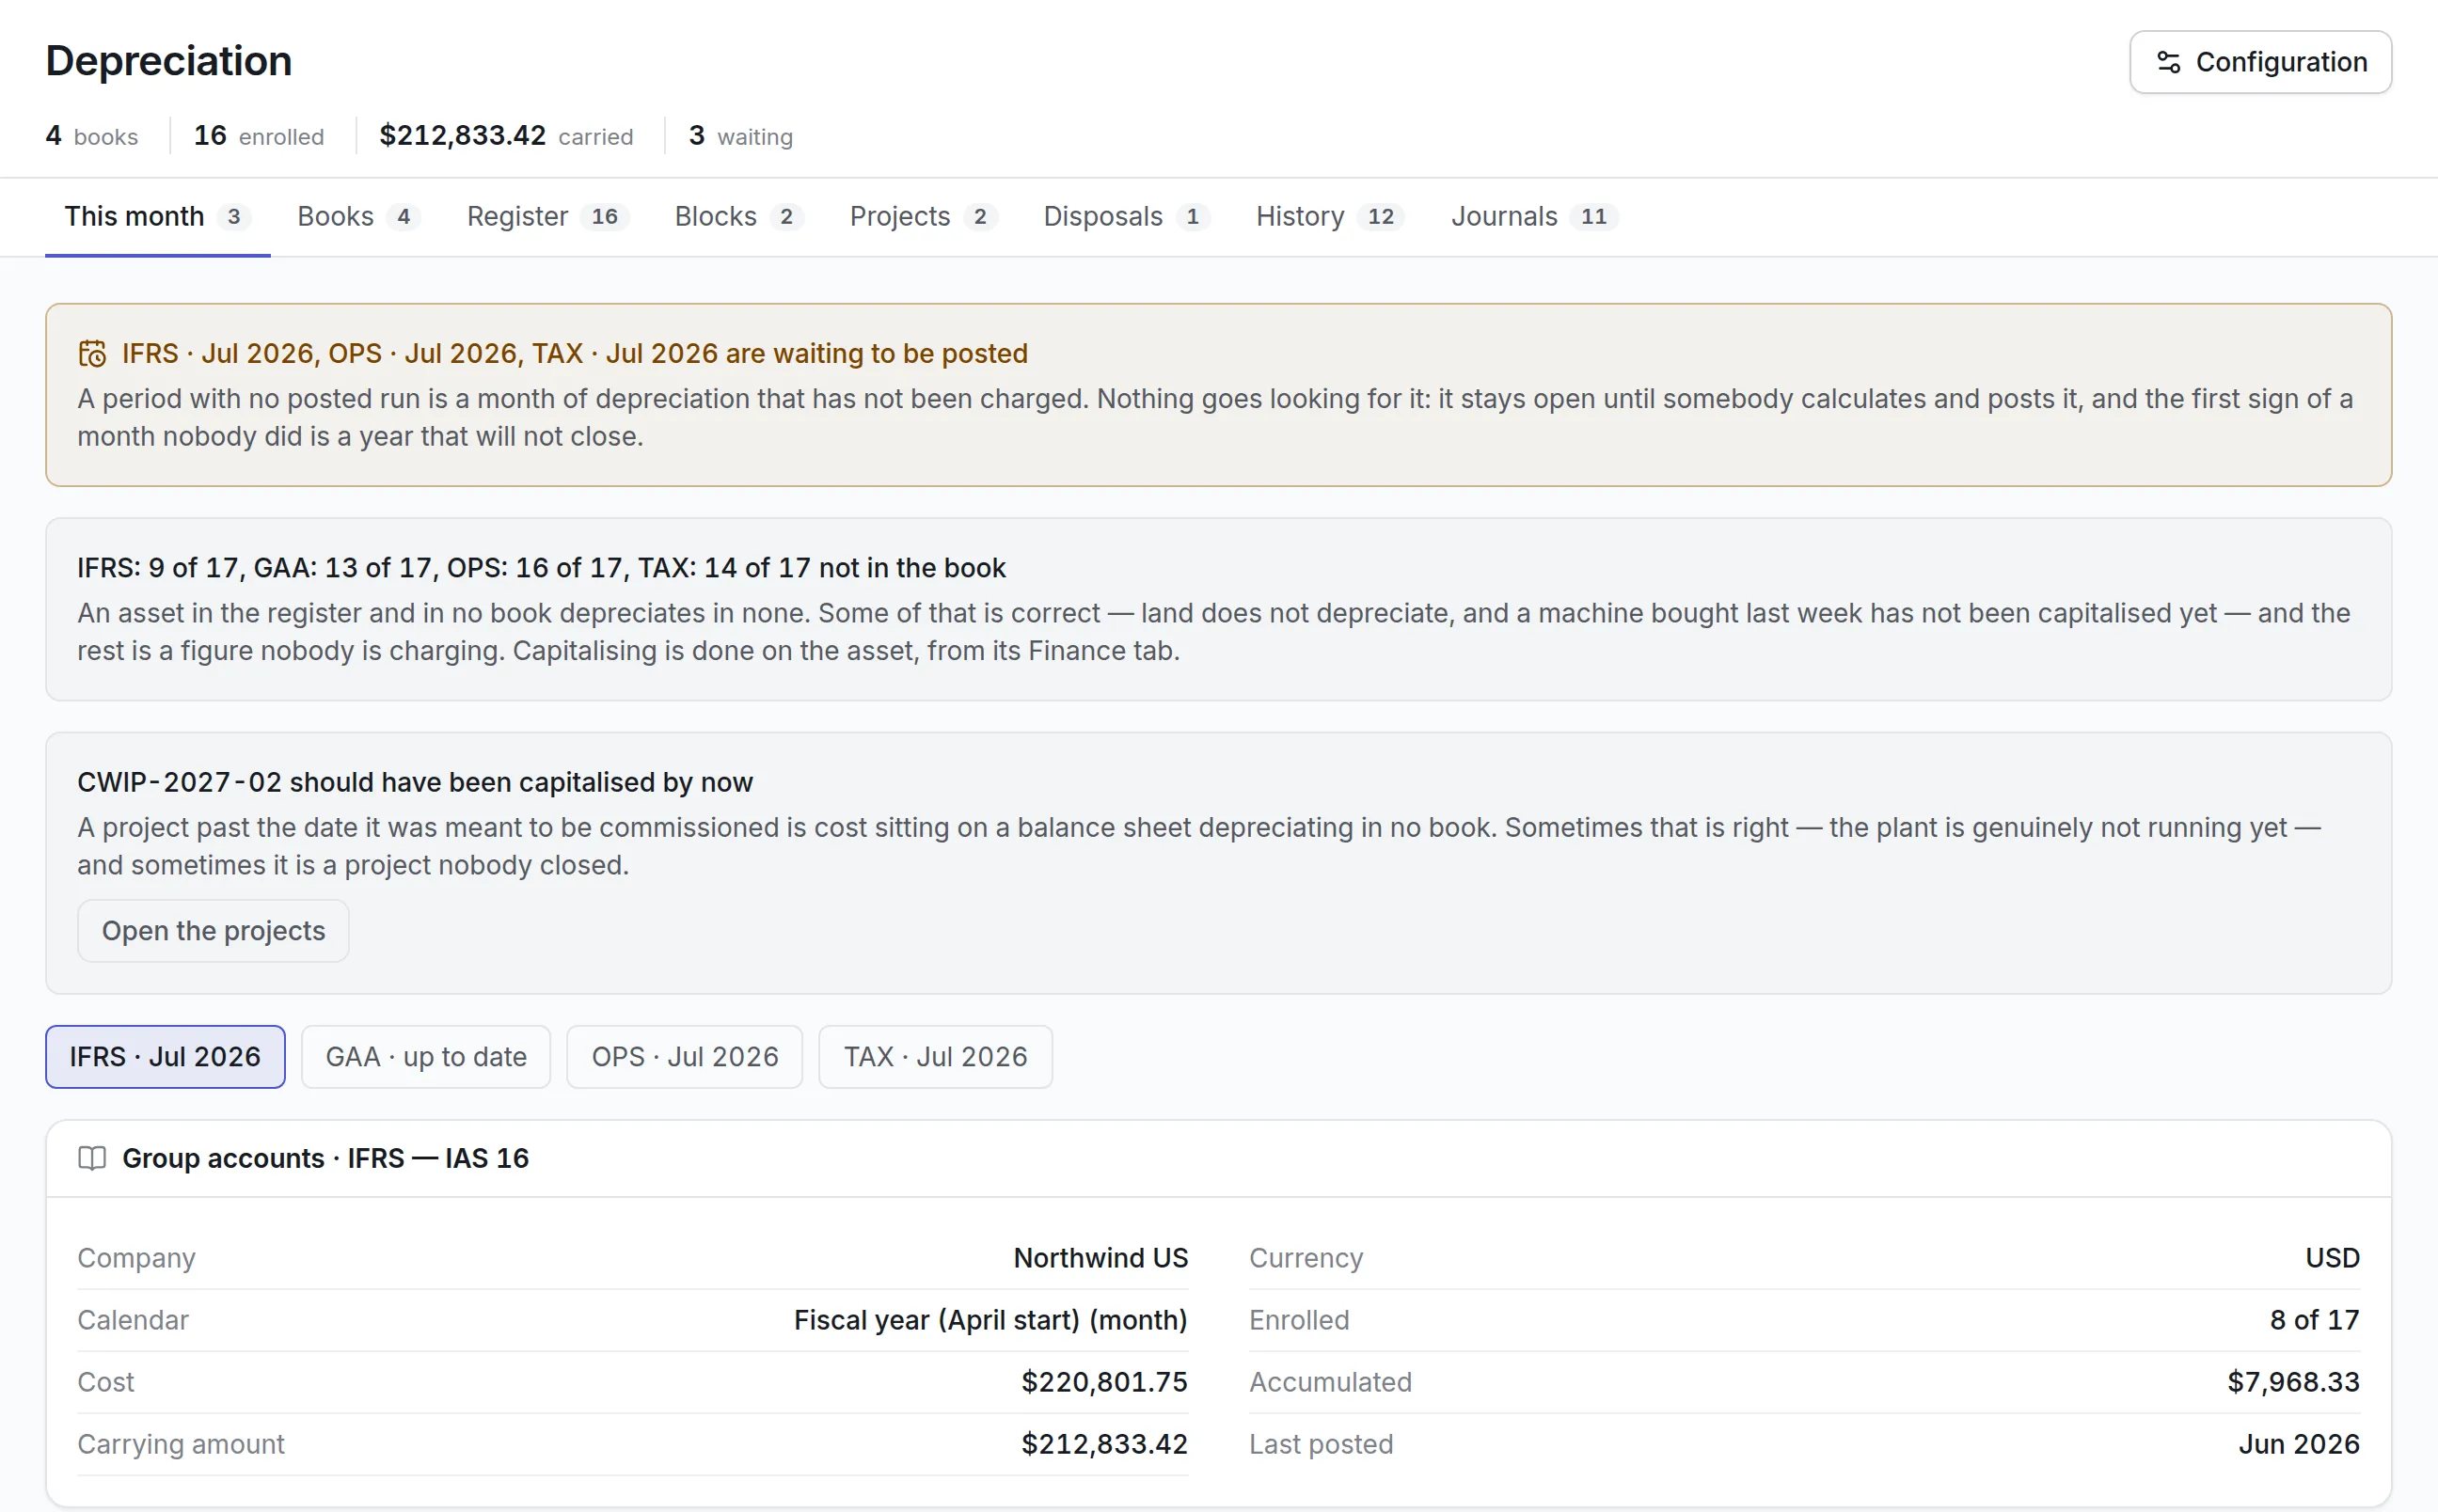
Every record keeps an audit trail of who changed what and when. Standard reports include the asset verification results, the verification round summary, the depreciation register and disposals by reason, so the evidence an auditor asks for is already in one place. The fixed asset management software page covers depreciation books, disposals and journals. For an example from the field, read how a client ran rural asset audits with Asset Infinity.
Frequently Asked Questions
What is a fixed asset audit checklist?
It is a list of every check in the audit: register completeness, ledger reconciliation, additions, disposals, the physical count, depreciation and sign-off. Using the same checklist each year makes results comparable.
How often should fixed assets be audited?
At least once a year for a full count, usually before year-end. Portable and high-value assets such as laptops and tools benefit from quarterly sample counts.
What is the difference between an asset inventory audit and a fixed asset audit?
An asset inventory audit counts what you own against the register. A fixed asset audit uses that count as evidence, then also tests valuation, depreciation, ownership and the match with the general ledger.
Who performs an internal audit of fixed assets?
Finance usually leads it, with the internal audit team if there is one, and site or department staff do the counting. The people counting should not be the only custodians of the assets they confirm.
What happens to assets that are not found?
They are investigated first, because many turn up at another site. Assets still missing are written off with management approval, and the reason is recorded so the auditor can follow it.